
Managing Workers’ Comp Costs in Florida: A Practical Guide for Mid-Sized Employers

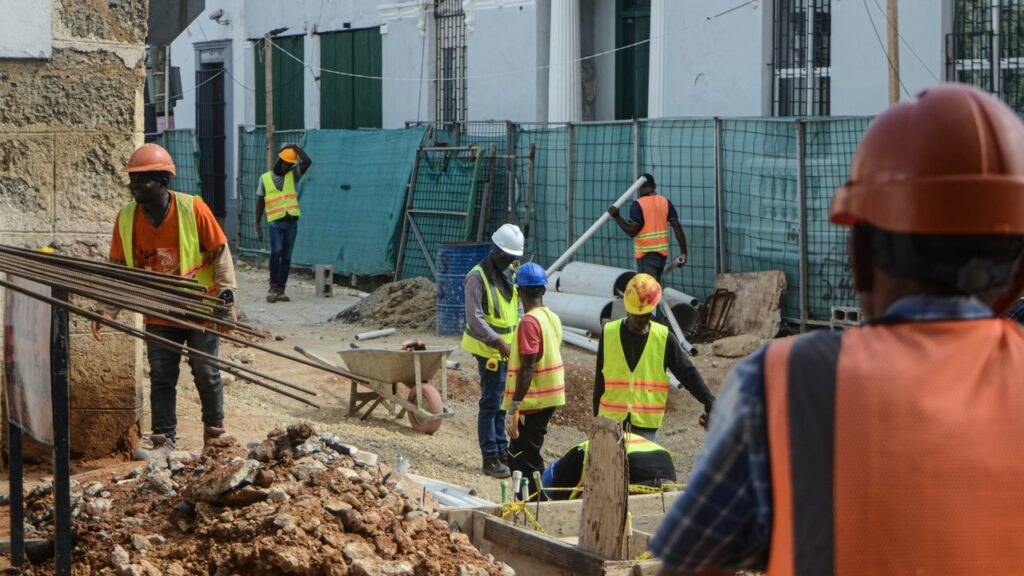
A construction crew in hard hats and high-visibility vests works on a job site.

For mid-sized Florida employers, workers’ compensation is a cost you can shape, not just a fixed line item. Your premium depends on payroll, class codes, and claim history, and you can influence all three. Each industry gets there differently:

  • Construction and service contractors: falls, ladders, and heavy equipment.
  • Apartments and real estate: maintenance staff slips, lifting, and ladder work.
  • Sports and fitness: strains and equipment handling.
  • Multi-unit restaurants and retail: kitchen burns, slips, and cuts, plus stocking and lifting.
  • Wholesale and manufacturing: warehouse lifting and forklifts.

Here’s how the main levers work in Florida.

1. Understand your experience mod

Most mid-sized employers are experience rated. NCCI compares your actual losses, typically from a three-year experience period, with the losses expected for a business of your size and type. The result is your experience modification factor, or “mod.” A 1.00 is average. A 0.85 lowers your premium by 15%, and a 1.20 raises it by 20%.

Frequency hurts more than severity. The formula gives full weight to the first part of each claim (the “primary” portion, up to a split point) and only partial weight to the excess above it. That means several small claims usually move your mod more than one large claim.

Illustrative example only (hypothetical numbers, not a Florida rating): in a simplified model, five $10,000 claims pushed a mod to about 1.25, while a single $150,000 claim raised it to only about 1.04. Your actual results depend on Florida’s current split point and the values on your own worksheet.

Medical-only claims get a break. Under NCCI’s Experience Rating Adjustment (ERA), only 30% of a medical-only claim’s primary and excess amounts count in the mod. NCCI says most states have approved this adjustment. Check your own experience rating worksheet to confirm it applies to you.

2. Make return-to-work a real program

A claim stays medical-only when the injured worker doesn’t lose wages. A modified or light-duty program keeps people doing real, productive work while they recover, so lost-time benefits never start. That keeps claims at the 30% weight and usually helps recovery.

A few cautions:

  • Report every injury to your carrier. Florida law requires employers to report an injury to their carrier within 7 days of learning about it (s. 440.185(2), F.S.), and handling claims “off the books” can backfire.
  • Light duty means actual work for actual pay. Paying an injured employee to stay home isn’t the same thing, so talk with your carrier first.
  • Write the program down, train supervisors and store managers, and have transitional-duty tasks ready at every location before you need them.

3. Get ahead of the premium audit

Your premium starts as an estimate. At the end of the term, the carrier audits your actual payroll and classifications. Surprises here are a common source of unexpected bills.

  • Track payroll by class code. Where a business has more than one classification, splitting payroll generally depends on clear records. Without them, payroll can end up in a higher-rated class.
  • Multi-location operations: restaurant groups, retail chains, and plants should track payroll and job duties consistently at each site. A driver, a warehouse worker, and an office employee can fall in very different classes.
  • Keep subcontractor files complete (see the next section). Uninsured subs are a frequent source of audit charges.
  • Contractors: ask your carrier whether you qualify for Florida’s Contracting Classification Premium Adjustment Program, a credit for contractors that pay higher wages.

What’s happening with Florida workers’ comp rates for 2027

Florida’s Office of Insurance Regulation (OIR) scheduled a virtual public rate hearing for Tuesday, Oct. 27, 2026, at 10 a.m. ET on the National Council on Compensation Insurance (NCCI) rate filing for 2027. In that filing, NCCI requests an overall average decrease in rate levels of 7.4% for the voluntary market, for new and renewal workers’ comp policies written in Florida effective Jan. 1, 2027. As of this writing, OIR’s final decision is pending. Check OIR’s hearing page for the outcome.

A few things to keep in mind:

  • It’s a proposal, pending OIR review. OIR reviews the testimony and public comment before issuing its decision, and it can approve the filing or require changes.
  • You can weigh in. The public comment record is open until Nov. 10, 2026, at 5 p.m. ET; see OIR’s hearing page for how to submit comments. OIR notes that written communications to the office are public record.
  • It’s a statewide average. Rates for individual class codes vary, and your own premium still depends on your payroll, classifications and experience mod.
  • For context: OIR approved a 6.9% average statewide decrease effective Jan. 1, 2026.

The levers in this guide matter whatever the final 2027 number turns out to be.

4. Manage subcontractors and certificates

Under Florida Statutes section 440.10, when a contractor subcontracts work, the employees of an uninsured subcontractor are treated as the contractor’s employees for workers’ comp. Contractors must get proof of coverage or a valid exemption from each sub.

That matters for general contractors, property owners running renovations, material suppliers that install, and fitness operators using independent trainers. A good process:

  • Collect a certificate of insurance or a state exemption before work starts.
  • Check it on the Florida Division of Workers’ Compensation Proof of Coverage search, which shows the carrier, policy dates, and exemptions.
  • Track expiration dates and get updated certificates before policies lapse.
  • Remember that an exemption applies only to the named officer and doesn’t cover anyone else, including the sub’s employees. A sub with employees still needs a policy.
  • Look closely at “independent contractor” arrangements. Florida applies specific statutory criteria, and some arrangements (for example certain owner-operators under a qualifying written contract) are excluded only when those criteria are met.

5. Build safety around your real losses

Since claim frequency drives the mod, preventing small injuries is often worth more than any premium credit. Start with your loss runs, then focus where your group’s injuries happen:

  • Construction: fall protection, ladder safety, and pre-task planning.
  • Apartments and real estate: slips, lifting, and ladder use by maintenance staff.
  • Sports and fitness: equipment handling, strains, and facility setup.
  • Restaurants: OSHA points to burns from fryers and hot surfaces, slips on wet or greasy floors, and cuts during food prep.
  • Retail: stocking, lifting, ladder use, and forklift traffic in stores and stockrooms.
  • Wholesale and manufacturing: OSHA identifies overexertion from lifting and being struck by forklifts as the most common warehouse injuries. Forklift operators must be trained and evaluated under federal rules.

For multi-unit businesses, standardize training and incident reporting and compare loss runs by site.

6. Know who must carry coverage

Under section 440.02, construction employers must carry workers’ comp once they have one employee, and most other employers once they have four. In construction, corporate officers and LLC members count as employees unless they hold a valid exemption. And as noted above, under section 440.10 a contractor is responsible for the workers of any uninsured subcontractor on the job.

The bottom line

Keep claims small and medical-only where you can, keep clean records at every location, verify every subcontractor, and build safety around your real losses.

Let’s look at your numbers

McGriff-Williams Insurance is an independent agency in Gainesville since 1983. If you’d like a second set of eyes on your mod worksheet, loss runs, or audit, give our Gainesville office a call at (352) 371-7977 or request a quote. We’re glad to walk through it with you.


This article is general information, not legal or insurance advice. Mod values shown are illustrative and are not Florida rating calculations. Rules and rating values change, so review your situation with your carrier, NCCI, or a licensed professional.

Sources

  • Florida Statutes s. 440.02 (Definitions): https://www.flsenate.gov/Laws/Statutes/2026/440.02
  • Florida Statutes s. 440.10 (Liability for compensation): https://www.flsenate.gov/Laws/Statutes/2026/440.10
  • Florida DWC, Coverage Requirements: https://www.myfloridacfo.com/division/wc/employer/coverage-requirements
  • Florida DWC Proof of Coverage search: https://dwcdataportal.fldfs.com/ProofOfCoverage.aspx
  • Florida Statutes s. 440.185 (notice of injury): https://www.flsenate.gov/Laws/Statutes/2026/440.185
  • NCCI, ABCs of Experience Rating: https://www.ncci.com/Articles/Documents/UW_ABC_Exp_Rating.pdf
  • Florida OIR, 2026 workers’ comp rate decision (6.9% decrease effective Jan. 1, 2026), press release Nov. 17, 2025: https://floir.gov/newsroom/archives/item-details/2025/11/17/commissioner-mike-yaworsky-approves-6.9–rate-decrease-for-florida-workers–compensation-policies–marking-9th-consecutive-year-of-decreases
  • Florida OIR, National Council on Compensation Insurance 2026 Public Rate Hearing (virtual hearing Tue Oct. 27, 2026, 10 a.m. ET; NCCI requests a 7.4% overall average decrease in rate levels for the voluntary market, new and renewal policies effective Jan. 1, 2027; comment record open until Nov. 10, 2026, 5 p.m. ET; comment instructions on the page), accessed Oct. 21, 2026: https://floir.gov/events/national-council-on-compensation-insurance-public-rate-hearing-2026
  • Florida Administrative Register, OIR notice of hearing on the NCCI filing (filing received Aug. 21, 2026): https://flrules.org/Gateway/View_notice.asp?id=31499021
  • NCCI, Summary of the Florida Workers Compensation Rate Filing Recommendation Effective January 1, 2027: https://www.ncci.com/Articles/Documents/II_StateAdvisoryForumState_FL_2026.pdf
  • NCCI, Insights From NCCI’s Experience Rating Plan Review (ERA): https://www.ncci.com/Articles/Pages/Insights-Exp-Rating-Plan-Review.aspx
  • OSHA, Restaurant Safety eTool (Cooking): https://www.osha.gov/etools/young-workers-restaurant-safety/cooking
  • OSHA, Warehousing: https://www.osha.gov/warehousing
  • OSHA, Powered Industrial Trucks (Forklifts): https://www.osha.gov/powered-industrial-trucks
Year-End Insurance Checklist for Florida Contractors

From the I-75 corridor in Marion County to the job sites around Jacksonville and St. Johns County, North Central and Northeast Florida contractors have had a busy year. Busy years are also when insurance paperwork slips: a sub’s certificate expires, an exemption runs out, or payroll outgrows the policy estimate.

Before you start bidding 2027 work, here’s a practical checklist for general contractors, site work and underground utility contractors, electricians, HVAC and plumbing contractors, and concrete, fencing and pool companies.

1. Know Florida’s Construction Rule for Workers’ Comp

Florida treats construction differently. Outside construction, workers’ compensation generally applies once a business has four or more employees. In the construction industry, it applies once you have one employee (section 440.02, Florida Statutes). Every contractor and subcontractor doing construction work in Florida has to secure and maintain coverage for its employees (section 440.10).

If your crew or your services grew this year, make sure your policy reflects it.

2. Check Officer Exemption Expiration Dates

Many contractors run as corporations or LLCs with officers who have elected to be exempt from workers’ comp. A few Florida rules to keep in mind:

  • In construction, no more than three officers of a corporation (or group of affiliated corporations) can be exempt. Each must own at least 10% of the company and be listed as an officer with the Florida Division of Corporations. For LLCs, the member must own at least 10%.
  • A construction exemption certificate is valid for two years and expires at midnight on the date shown. The Florida Department of Financial Services (DFS) sends a notice at least 60 days before it expires.
  • Applications and renewals are filed online with the DFS Division of Workers’ Compensation, carry a $50 fee, and require a short online coverage-and-compliance tutorial.
  • An exemption applies only to the officer named on it, for the companies listed on it. It is not a contractor’s license.

To do: pull up each officer’s certificate, note the expiration date and put a renewal reminder on the calendar.

3. Get Your Subcontractor Certificates in Order

This is where we see the most surprises at audit time.

Under Florida law, when a contractor sublets work, the contractor is responsible for workers’ comp for the subcontractor’s employees on that job, unless the subcontractor has its own coverage (section 440.10). The law also says the contractor must require subs to show proof of workers’ comp, and an exempt officer must give the contractor a copy of the exemption certificate.

A simple routine helps:

  • Collect a certificate of insurance (COI) for workers’ comp and general liability from every sub before they start work, and track the expiration dates.
  • Verify workers’ comp coverage and exemptions on the DFS Proof of Coverage database. It takes about a minute.
  • Keep copies organized by sub and by job. Your auditor will ask for them.
  • Check your contracts. If you require subs to name you as an additional insured or carry certain limits, confirm their certificates show it.

Uninsured subs can show up as added premium at audit, and worse, as a claim on your own policy.

4. Prepare for Your Premium Audit

Workers’ comp and many general liability policies start with an estimate of your payroll, sales or subcontracted costs. After the policy year ends, the carrier audits your actual numbers, usually every year for contractors (and on-site for larger policies), and adjusts the premium up or down.

You can make audits smoother, and avoid surprises, by having these ready:

  • Payroll records by employee and by job duty (class code). If someone works in more than one trade, keep time records that show hours in each. Without them, the auditor can put all of that person’s pay in the highest-rated class.
  • Overtime records that show the overtime premium separately (the extra “half” is left out of workers’ comp payroll only if your records break it out), plus officer payroll and copies of any officer exemptions.
  • A list of every subcontractor you paid, with amounts and their certificates. Make sure each certificate or exemption was in force on the dates the sub worked for you. If the auditor can’t get access to your records, Florida lets the carrier charge up to three times your estimated annual premium.
  • Notes on any change in operations: new services, new counties, larger projects.

If payroll has grown a lot since your policy started, call us before the audit. Updating your estimate mid-term spreads the extra premium across your remaining payments, so you won’t face one large bill at audit. It also keeps your certificates and limits in line with your real size.

5. Look Ahead to 2027 Bids

Before the new year’s contracts land on your desk, review:

6. Don’t Forget the Weather

Hurricane season runs through November 30, and Hurricane Isaias was a reminder that storms can arrive late. Review your jobsite storm plan: securing materials and equipment, protecting partially completed work, and knowing how your builders risk and equipment policies handle named-storm deductibles.

Why It Matters

DFS enforces workers’ comp coverage in construction, and a business found without the required coverage can face a stop-work order and penalties (section 440.107). A well-organized file also keeps your premium accurate and your projects moving.

Let’s Review Your Program Before Year-End

McGriff-Williams has worked with Florida contractors since 1983. We’re an independent agency, so we compare options from multiple insurance companies for workers’ comp, general liability, auto, equipment, builders risk and umbrella coverage. Then we help you stay organized all year: certificates, audits, exemptions and renewals. Call us at (352) 371-7977 or request a business insurance review. You can also learn more about our workers’ compensation and business insurance services.


General information, not legal advice. Coverage depends on the policy issued, its terms and underwriting. Florida workers’ compensation rules are set by Chapter 440, Florida Statutes, and DFS rules; confirm your situation with your agent, carrier or the DFS Division of Workers’ Compensation. McGriff-Williams Insurance is an independent insurance agency licensed in Florida. Information current as of October 2026.

Protecting Trading Cards at Home, in the Mail and in the Shop

Graded trading cards in clear protective cases on a desk beside a padded box and a magnifying loupe.

On October 13, 2026, a FedEx driver found that two pallets of graded trading cards, including sports and Pokémon cards, and some packages from a third pallet had been taken from his truck, which was parked at or near PSA’s facility in Santa Ana, California, according to police and news reports. The initial estimated value was $963,000, and police have said the final figure may be higher. These details are as reported, and the facts are still developing. According to the Los Angeles Times, the cards had been graded and were set to be returned to their owners, and PSA told customers in a letter quoted by the LA Times that a FedEx vehicle transporting PSA orders was burglarized “after leaving our PSA facility in Southern California.” FreightWaves reported on October 20 that police were still working to determine when and where the theft happened, and as of October 21, 2026, no arrests had been reported. PSA said in a public statement that it has deactivated the stolen cards’ certificates and is arranging compensation for affected customers based on fair market value.

It’s a reminder that cards spend time in many places: at home, at a show, in the mail and at a grading company. Each can be covered differently, or not at all.

1. Collectors: at home, traveling and at card shows

Keep a record of what you own. Front and back photos, certificate numbers, receipts and dated sale comparisons make a claim much easier to document.

Think about where the cards live. The FDIC notes that safe deposit box contents aren’t covered by FDIC deposit insurance and that banks generally don’t insure them, so ask your agent about coverage for valuables kept there.

At shows and while traveling: keep high-value cards with you rather than in a parked car, don’t post your location or haul in real time, and check whether your policy covers cards away from home.

2. Shipping: what “declared value” does and doesn’t do

Carrier limits for collectibles can be low. For example, FedEx’s 2026 Service Guide (effective Jan. 5, 2026, updated Sept. 11, 2026; checked Oct. 21, 2026) limits its liability to $100 per package unless a higher value is declared, up to $50,000 per package for most U.S. services. But shipments containing “collector’s items such as coins, stamps, sports cards, souvenirs, and memorabilia” are limited to a maximum declared value of $1,000, so a card worth $5,000 can’t be declared for more than $1,000. The same guide caps anything shipped in a FedEx Envelope or Pak at $500.

Declared value isn’t insurance. FedEx’s terms say so directly, and the shipper must prove actual damages. UPS and the U.S. Postal Service publish their own limits, options and lists of items they won’t accept. These terms change, so check the carrier’s current rules before you ship.

A grading company covers only part of the trip. Under PSA’s published terms (updated April 22, 2026), for example, the customer “bear[s] the sole cost and risk” of loss on the way in, even with a PSA label, and PSA’s responsibility starts once the item is unpacked and confirmed received. While PSA has the card, compensation is capped at the lower of fair market value or the “Maximum Insured Value” of the service level you chose, so PSA advises choosing a level above the card’s expected value after grading. For the return trip, you can have PSA ship and insure the package, buy your own insurance, or use your own shipping account, which PSA doesn’t insure.

These are general published terms, and how they apply to any particular shipment, including the Santa Ana loss, hasn’t been made public. Your own policy may fill some of these gaps, depending on how it treats property in transit and held by others. Ask before you send cards out.

3. Card shop owners: inventory, customers’ cards and shipping

NBC Los Angeles reports that a handful of Southern California card shops have been targeted by break-ins in the past year. Things for shop owners to look for:

  • How inventory is valued. Some policies value stock at replacement cost, some at depreciated value, and some dealer policies at market value, often with a coinsurance requirement, so keep your insured amount in line with current values. Some also limit or exclude theft of categories like stamps or collectibles.
  • Security conditions. Some policies written for collectibles dealers set a lower theft limit for anything not locked in a safe, or require an alarm and safe, with coverage reduced if those conditions aren’t met. If you open a second location or move your safe, make sure the policy is updated to match.
  • Customers’ cards in your care. For consignments, holds and grading submissions, note that standard general liability policies exclude damage to personal property in your care, custody or control, and business property policies may include only a small amount for customers’ property unless you increase it. Bailee coverage or a “property of others” provision may help, along with written records of what you’re holding and for whom. Cards sent out for grading are away from your shop and in transit, so check whether your coverage follows them.
  • Shipping and shows. Inland marine coverage can be written to follow inventory in transit or at shows, usually with conditions. Some policies cover shipments well only when sent signature-required or by certain methods, and very little otherwise. There’s often a separate, lower limit for cards away from your shop, such as at a show, plus rules about unattended vehicles.
  • Theft and crime. Break-ins by outsiders are usually handled under your property policy’s theft coverage, if your policy includes theft, subject to the limits above. Some policies for collectibles dealers exclude employee theft, unexplained losses and shortages found only in an inventory count, so a separate crime policy may be needed. Crime policies have their own inventory-count exclusion, so keep item-level records. They can also cover theft of money from the premises or robbery.
  • Who’s named on the policy. Make sure the business that owns the inventory is named on the policy. If the stock belongs to your LLC but only you are named, that can complicate a claim.

4. Common homeowners gaps for collectors

A standard homeowners policy can cover a card collection as personal property, but there are common limits to know about. Many Florida homeowners policies are based on standard industry forms, and the points below describe how those forms commonly work. Your own policy may read differently, and its wording controls. Most policies set lower limits for categories such as money, coins, stamps, jewelry and business property. Trading cards usually aren’t a named category, but check how your policy treats them.

  • Business property limits. Homeowners policies usually set a much lower limit for property used mainly for a “business,” often $2,500 at home, with a separate, lower limit away from home that varies among Florida policies. Many policies define “business” broadly, including a trade done full-time, part-time or occasionally, and other paid activity once it earns more than a set amount in a year. If you buy and sell cards regularly, online, at shows or through consignment, the cards you hold for resale could be treated as business property, and a personal policy may limit or exclude them. It’s worth asking about business coverage for that part of your collection.
  • Mysterious disappearance. In a typical homeowners form, theft coverage includes property missing from a known place when it’s likely it was stolen. A card that simply goes missing, with nothing to suggest a theft, may not be covered.
  • Breakage. Most HO-3 policies cover personal property only for a list of named causes of loss, such as fire, smoke or theft. Accidentally dropping a slab isn’t on that list, so the damage may not be covered. Some policies offer broader “open perils” coverage for personal property, but even that can exclude breakage of fragile items. Your policy’s wording controls.
  • Theft away from home. Policies differ here. Some cover theft of your belongings away from home much as they would at home. Others cap it at a fraction of your personal property limit, and some Florida policies don’t cover theft away from your home at all. Policies can also set lower limits for property kept at a second home or in a storage unit. Check your policy before you take cards to a show, a hotel or a storage unit.
  • Replacement cost may not apply. Many policies offer replacement cost for personal property, but the standard replacement cost endorsement many policies use treats collector’s items and memorabilia whose age or history adds to their value as ineligible. Those are usually settled at actual cash value instead. Florida law also generally lets homeowners remove personal property (contents) coverage from their policy by signing a written statement, so it’s worth confirming that yours includes it.

Options that may help. Some policies let you add a scheduled personal property endorsement (sometimes called a floater) that lists valuable items or a collection individually, with its own amount of coverage. A floater can also be bought as a separate policy. These often cover more causes of loss than the homeowners policy itself, sometimes with no deductible. Not every policy allows scheduling, though, and not every insurer will schedule trading cards. Some floaters still exclude breakage of fragile items, or loss while shipping or on display.

A standalone collectibles policy is another option, and these value cards in different ways. Some use agreed value for listed items, meaning you and the insurer settle on an item’s value when it’s added, not after a loss. Others insure the whole collection on a blanket basis and pay market value at the time of a loss, often with no list required for lower-value items. Still others pay the lower of the listed amount or the item’s value at the time of loss, so ask which applies. Causes of loss, exclusions, eligibility and availability vary by company and by state. Card values change, so it’s worth reviewing your listed values and total limit regularly.

Questions to ask about collectibles coverage:

  • Is there a per-item limit on blanket coverage, and when should a card be listed individually?
  • What documentation or appraisal is needed, and how often should values be updated?
  • Are cards covered in the mail, at a show (including while displaying or selling) and while a grading company has them? Are there shipping-method or packaging rules?
  • Are accidental breakage and unexplained loss covered, and what deductible applies?

Damage from humidity, gradual deterioration or insects is commonly excluded, so storage conditions matter.

Let’s review your coverage

McGriff-Williams Insurance is an independent agency in Gainesville since 1983. Whether you collect, sell or run a card shop, a licensed member of our team can review your current home or business coverage with you, including how it treats your cards. Call (352) 371-7977 or contact us.

This article is general information, not a statement of coverage. Your policy’s terms, conditions and endorsements control. Coverage options vary by company and are subject to underwriting and availability. News details are as reported as of October 21, 2026 and may change.

Sources

  • NBC Los Angeles, “Trading cards worth nearly $1 million stolen from FedEx truck, PSA says” (Oct 19, 2026, updated Oct 20), accessed Oct 21, 2026: https://www.nbclosangeles.com/news/local/trading-cards-stolen-from-fedex-truck-psa/3958318/
  • FreightWaves, “Nearly $1M in Pokémon and sports cards vanish from FedEx truck, driver discovers missing lock” (Oct 20, 2026), accessed Oct 21, 2026: https://www.freightwaves.com/news/nearly-1m-in-pokemon-and-sports-cards-vanish-from-fedex-truck-driver-discovers-missing-lock
  • People, “Pokémon and Sports Cards Worth Nearly $1 Million Stolen from FedEx Truck, Police Say Value Could Be Higher” (Oct 20, 2026), accessed Oct 21, 2026: https://people.com/nearly-1-million-worth-of-pokemon-sports-cards-stolen-from-fedex-truck-california-police-say-12185357
  • Los Angeles Times, Steve Henson, “Almost $1 million in rare sports and Pokémon cards stolen from FedEx truck in Santa Ana” (Oct 20, 2026), accessed Oct 21, 2026: https://www.latimes.com/sports/story/2026-10-20/1-million-dollars-sports-pokemon-trading-cards-stolen-fedex-santa-ana
  • FedEx Service Guide 2026 (effective Jan. 5, 2026; updated Sept. 11, 2026), Terms and Conditions, “Declared value and limits of liability (not insurance coverage),” items A, B, C, E, G.11 and H, accessed Oct 21, 2026: https://www.fedex.com/content/dam/fedex/us-united-states/services/Service_Guide_2026.pdf
  • PSA Submission Services Terms and Conditions (last updated April 22, 2026), sections 2, 5, 6, 7 and 10, accessed Oct 21, 2026: https://www.psacard.com/termsandconditions
  • FDIC, “Five Things to Know About Safe Deposit Boxes, Home Safes and Your Valuables” (last updated Aug. 1, 2023), accessed Oct 21, 2026: https://www.fdic.gov/consumer-resource-center/five-things-know-about-safe-deposit-boxes-home-safes-and-your-valuables
  • Florida Department of Financial Services, “Homeowners’ Insurance: A Toolkit for Consumers,” accessed Oct 21, 2026: https://www.myfloridacfo.com/docs-sf/consumer-services-libraries/consumerservices-documents/understanding-coverage/consumer-guides/english—homeowners-insurance-toolkit.pdf
  • Florida Department of Financial Services, Office of the Insurance Consumer Advocate, “Homeowners Insurance Policy Endorsements” (Personal Property Replacement Cost Coverage; Personal Property Exclusion), accessed Oct 21, 2026: https://myfloridacfo.com/division/ica/fullcoverage/homeowners/policyendorsements
  • Insurance Information Institute, “Special coverage for jewelry and other valuables,” accessed Oct 21, 2026: https://www.iii.org/article/special-coverage-for-jewelry-and-other-valuables

When the Freezer Gets Hacked: Insurance Gaps Florida Businesses Should Know

From McGriff-Williams Insurance, an independent agency in Gainesville since 1983. Where confidence grows.

When most business owners picture a cyberattack, they think of locked computers, stolen customer data or a ransom note. In October 2026, an attack in France showed that a hack can reach something far more physical: the freezer case.

If you run restaurants or retail locations in Florida, own apartment or commercial buildings, store goods cold, or install and service building controls, this story is worth a few minutes. The bigger lesson isn’t about technology. It’s about which insurance policy, if any, pays when a hack ruins your inventory. We’ll walk through what happened, where the gaps can be, and the questions to bring to your next coverage review.

What Happened in France

On the night of Sunday, October 11, into Monday, October 12, 2026, attackers remotely accessed the refrigeration controls at hundreds of supermarkets across France. Reported counts vary, from at least 350 stores to roughly 700, according to news reports.

According to public reporting, the attackers reached controllers that were connected to the internet. They switched refrigerated and frozen cases into defrost mode, removed the limits that normally keep temperatures in check, and set some cases to around 122°F (50°C). Early findings suggested alarms were disabled or avoided. Cases ran hot for roughly four to six hours before morning staff discovered the problem. Food thawed and began to cook. A few stores reported small fires, which set off sprinklers and caused water damage.

Most stores stayed open. They threw out affected product, restocked, and recovered within hours to about a day. The losses still added up. One chain’s leadership estimated about €50,000 in losses for an average store. Another reported up to €200,000 for a single large hypermarket, and industry leaders said the total could reach tens of millions of euros.

Several things were still unknown as of mid-October 2026:

  • Who did it. No one had claimed responsibility, and investigators had not publicly named a suspect. Attribution remains unconfirmed.
  • Exactly how. Officials had not publicly confirmed the precise method used to get in.
  • Why. The motive is unknown. No ransom demand was reported.

The Paris prosecutor’s office opened a cybercrime investigation, and France’s national cybersecurity agency warned that attack campaigns were probably still underway. Equipment makers said many affected units were older models that no longer receive security updates. Security researchers also pointed to devices left exposed to the public internet and, in some cases, apparent default passwords. France’s economy minister called it “a wake-up call for everyone.”

Why It Matters Here in Florida

Grocery stores, restaurants, convenience stores and cold-storage facilities here can rely on connected refrigeration controls, and some are monitored remotely by a refrigeration contractor. That’s convenient, but it also creates a door into the system that needs to be locked.

The U.S. Cybersecurity and Infrastructure Security Agency (CISA) has published advisories describing security flaws in commercial refrigeration controllers, along with available fixes. Whether those particular flaws played a role in France has not been confirmed. Either way, the risk isn’t limited to Europe.

Here’s how the lesson can apply to the Florida businesses we work with:

  • Multi-unit restaurants and retail. If one remote connection reaches the coolers at several of your locations, one bad night could mean spoiled stock at all of them at once. That can change how your deductibles and waiting periods apply.
  • Real estate and apartments. If your buildings use connected HVAC, access or other building controls, ask who can reach those systems remotely, and whose policy would respond if a shared system were tampered with.
  • Wholesale and light manufacturing. If you hold product in coolers or freezers, the same question applies: what happens to the inventory if the temperature controls are changed remotely?
  • Contractors who install or service controls. If your team has remote access to customers’ refrigeration, HVAC or building systems, your customers may start asking how that access is secured and what insurance stands behind it.

The Surprise: Whose Policy Pays for the Spoiled Food?

French grocery leaders said publicly that their insurers had told them this kind of loss was not covered. Insurance brokers told Reuters that cyber policies typically exclude physical losses. Here’s why that gap can exist in the U.S. as well:

  • Many cyber policies exclude physical damage. Spoiled food is tangible property. A cyber policy may pay for investigating the hack but not for the inventory you had to throw away.
  • Many property policies now exclude cyber events. In recent years, insurers have added cyber exclusions to many commercial property forms.
  • Spoilage coverage often has narrow triggers. Spoilage coverage is commonly tied to a mechanical breakdown or a power outage. In France, the equipment did what it was told to do. Whether a remote change to temperature settings counts as a “breakdown” depends on your policy wording.

The result is that the largest dollar loss, the spoiled stock, can fall between policies. French insurance commentators noted that lost profit on unsold goods might be recoverable in some cases, while the cost of the discarded stock itself might not be.

Fire can be different. Some property policies cover a fire that results from a cyber incident, and others don’t.

What a Cyber Policy May Help With

Depending on its terms, a cyber policy may still help pay for:

  • Forensic investigation to find out how the attackers got in
  • Restoring and reconfiguring affected systems
  • Some lost income while systems are down, usually after a waiting period
  • Legal and public relations help
  • Extortion costs, if a ransom is demanded

A lot depends on how your policy defines your “computer system.” Some definitions include equipment like refrigeration and building controls. Others may not, especially if a vendor owns or operates the device.

Questions to Ask About Your Coverage

Bring these questions to your next insurance review:

  1. Does my cyber policy treat connected equipment, like refrigeration, HVAC or building controls, as part of my computer system?
  2. Does it include any coverage for physical damage or spoiled inventory caused by a hack?
  3. Does my property or spoilage coverage exclude cyber events? If so, is any coverage given back?
  4. What triggers my spoilage coverage? Is it only mechanical breakdown or power outage?
  5. If 20 of my locations are hit in the same night, how do my deductibles and waiting periods apply?
  6. Does my policy have a war or state-sponsored attack exclusion, and how would it apply if a government blamed another country?

Don’t Forget Your Vendors

In France, discussion quickly turned to who was responsible for securing the equipment. Ask yourself:

  • Who has remote access to your refrigeration and building systems?
  • Does your service contract say who is responsible for security, updates and passwords?
  • Does your vendor carry insurance that could respond if its access is used in an attack?

France’s government cybersecurity alert also offered a useful reminder: check your insurance contract conditions before cutting off your refrigeration contractor’s remote monitoring connection. Some policies or service agreements may require that monitoring, so check with your agent and your contractor first.

We can help with the paperwork side of this, too. For property owners, we can review the insurance requirements in your leases. That review looks only at insurance terms. It isn’t legal advice, so have your attorney review the lease itself.

Practical Steps to Consider This Month

Talk with your refrigeration contractor and IT provider about these steps, drawn largely from French and U.S. government cybersecurity guidance:

  1. Make a list of every connected refrigeration and building controller you have, with make, model and software version.
  2. Get them off the open internet. Remote access should run only through a secured connection.
  3. Update or replace outdated units. Equipment that no longer gets security updates is hard to protect.
  4. Change default passwords and remove accounts nobody uses.
  5. Check defrost schedules and temperature limits, especially after any suspicious activity.
  6. Add an independent temperature alarm that doesn’t rely on the controller itself.
  7. Set an overnight plan so someone gets the alert and knows what to do.

If you’d like a starting point, ask us about our cyber risk assessment. It’s a review of your cyber exposures and how your insurance lines up with them, not a technical security audit or certification, so keep working with your IT provider and refrigeration contractor on the steps above.

If It Happens to You

Work with your refrigeration contractor and IT provider to cut off outside access to the affected systems, keeping your policy and contract conditions on remote monitoring in mind. Document everything: photos of cases, temperature readings, and a log of every item you discard with its cost. Notify your insurance agent and insurance companies promptly under every policy that might apply, including cyber, property and any spoilage or equipment breakdown coverage. Report the incident to law enforcement (for U.S. businesses, the FBI’s Internet Crime Complaint Center at ic3.gov).

Frequently Asked Questions

Does cyber insurance pay for food that spoils after a hack?
Often not. Many cyber policies exclude physical damage, and spoiled food is tangible property. A cyber policy may still help with investigation, system restoration and some lost income. It depends on your policy wording.

Would my spoilage coverage pay instead?
Maybe. Spoilage coverage is commonly tied to a mechanical breakdown or a power outage. Whether a remote change to temperature settings counts as a breakdown depends on the wording, and some property policies exclude cyber events altogether.

Was the French attack ransomware?
There’s no sign it was. No ransom demand was reported, no one had claimed responsibility, and attribution was unconfirmed as of mid-October 2026.

What should I do first?
Make a list of your connected refrigeration and building controls, ask who can reach them remotely, and review your cyber, property and spoilage coverage together, not one at a time.

Let’s Look at the Whole Picture

The lesson from France is that cyber, property and spoilage coverage can’t be reviewed in isolation. They need to work together. McGriff-Williams Insurance is an independent insurance agency serving Florida businesses from Gainesville. We can review your cyber, property and spoilage coverage side by side, help you spot possible gaps, and talk through your options in plain English. There’s no obligation.

Call (352) 371-7977 or request a quote.

McGriff-Williams Insurance
3501 W University Ave, Gainesville, FL 32607
(352) 371-7977 · Monday–Friday, 9 AM–5 PM
mcgriffwilliams.com


This article is for general educational purposes only and is not legal advice. Insurance coverage depends on the actual terms, conditions, limits and exclusions of each policy. Nothing here changes any policy or promises that any loss is or will be covered. Details of the French incident are based on public reports as of mid-October 2026 and may change as investigations continue.

Sources

Small Business Insurance New Year, New Risks – Why Your Policy Needs a January Review

Why Small Business Owners Should Review Their Commercial Insurance Coverage

The start of a new calendar year is more than just a fresh page—it’s a critical moment for small business owners to assess and adjust their operations. Your small business insurance policy should be at the top of this review list. As your business evolves, so do the liabilities you face, and inadequate commercial insurance coverage can leave your company exposed to financial loss.

January: The Best Time for a Business Insurance Audit

Why kick off the year with an insurance review? Your business operations in the previous year often involve changes that directly impact your risk profile:

  • Growth and Expansion: Did you hire new employees, increase inventory, or lease a larger office space?
  • New Equipment/Assets: Purchasing new machinery, technology, or vehicles changes the value of your assets that need protection.
  • Updated Services or Products: Launching a new offering may introduce professional or general liability risks not covered by your current policy.
  • Changing Regulations: New state or industry-specific compliance requirements might necessitate different forms of business liability insurance.

Key Areas to Update in Your Small Business Insurance Policy

A thorough January review helps identify gaps in your protection. Focus on these critical types of small business insurance:

1. General Liability Insurance (GLI)

Did your client interactions or on-site foot traffic increase last year? General liability insurance protects against claims of bodily injury or property damage for which your business could be held responsible. Verify that your current liability limits align with your updated exposure, especially if you moved to a new location or handle more high-value projects.

2. Commercial Property Insurance

This coverage protects the physical assets of your company—buildings, equipment, inventory, and supplies. Review the following:

  • Inventory Value: If sales surged, your current coverage limits might undervalue your stock, leaving you under-indemnified after a loss event.
  • New Asset Valuation: Have you purchased new computers, manufacturing equipment, or furniture? Update your asset schedule to reflect the current replacement cost.
  • Business Interruption Coverage: Has your revenue increased? This vital component, often bundled with property insurance, must reflect your current profitability to adequately cover lost income following a covered peril.
3. Workers’ Compensation Insurance

If your employee count changed, or if roles shifted to include higher-risk duties, your Workers’ Comp insurance classifications and premium will need an adjustment. Failing to accurately report payroll and job functions can lead to penalties or claims issues down the line.

4. Professional Liability (E&O) and Cyber Insurance

For service-based businesses (consultants, IT, marketing agencies), Professional Liability Insurance (Errors & Omissions) is crucial. If you begin offering new, higher-risk services (e.g., handling client data, providing complex advice), re-evaluate your limits.

Furthermore, with cyber threats rising, all small business owners should review their Cyber Liability Insurance to confirm it covers data breaches, regulatory fines, and business interruption from a cyber-attack.

Your Action Plan for a January Insurance Review

Don’t wait until a claim occurs to discover a coverage shortfall. Follow these steps to optimize your commercial insurance in the new year:

  • Document All Changes: Create a detailed list of new hires, large asset purchases, revenue changes, and any new services/products from the past 12 months.
  • Contact Your Broker: Schedule a dedicated review with your small business insurance agent or broker to discuss the documented changes.
  • Compare Quotes: The market is always changing. Use the new year as a trigger to quickly compare business insurance quotes to confirm you are getting competitive rates for the required coverage.
  • Confirm Deductibles: Verify that your current deductibles are financially manageable for your business.

Protecting your assets with the right coverage is a foundational element of a strong business plan. Start the year right by securing comprehensive small business protection.
