
OSHA Construction Fines Near Gainesville: What Local Data Shows

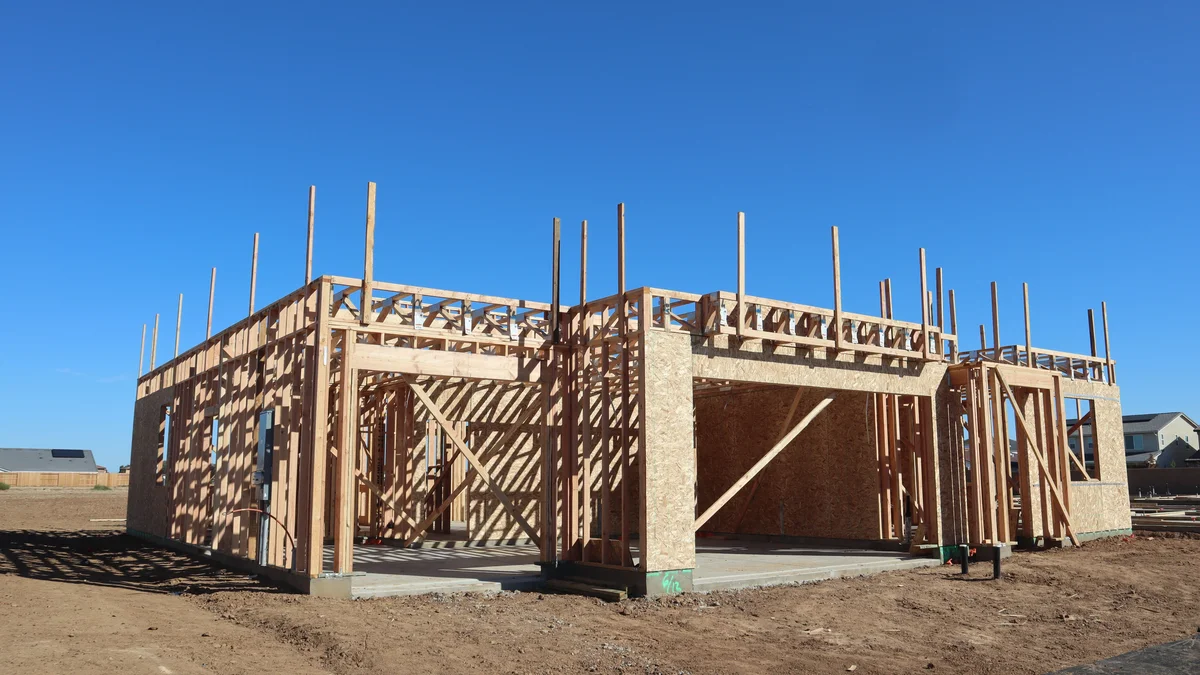
Wood framing of a new house on a cleared lot under a clear blue sky

If you run a construction company in North Central Florida, OSHA is closer than you might think. We pulled OSHA’s public enforcement data for federal OSHA construction inspections opened from January 2023 through mid-September 2026 at job sites within about 120 miles of Gainesville. That covers the area from Jacksonville and St. Augustine to Ocala, Daytona, The Villages, the Orlando area, the north side of Tampa, and Valdosta. Here’s what it shows and what you can do about it.

What the numbers show

  • 2,515 construction inspections in this data, and just over half (1,310) have at least one citation on record. Some of those cases are still open.
  • About $19.15 million in penalties as first issued, including items OSHA later deleted. The current total is about $13.69 million, reflecting settlements and final orders so far. It also includes open and contested cases that can still change.
  • About 44% of inspections were planned or programmed, and about 16% started with a complaint. Under OSHA’s national emphasis programs, inspectors may open an inspection when they see someone working at heights or an open trench.
  • OSHA’s maximum penalties that may be assessed after Jan. 15, 2026 are $16,550 per serious violation and $165,514 per willful or repeat violation (osha.gov/penalties, checked October 22, 2026).

Which OSHA office? In this data, every Alachua County construction inspection was handled by OSHA’s Jacksonville Area Office, and Marion and Levy county inspections were handled by the Tampa Area Office.

Five local patterns worth learning from

1. Trenches without protection. Cave-in protection citations were relatively rare here (57 items in nearly four years), but they were costly. Three of the five largest penalties outside roofing, as first issued, were trench cases, each over $140,000 before any settlement or final order. Under OSHA’s trench emphasis program, inspectors may open an inspection when they see an open trench or excavation.

2. Residential framing and carpentry falls. Roofers aren’t the only trade with big fall citations. In this data, 68 inspections of other trades, 53 of them framing contractors, included both a fall protection citation and at least one willful or repeat citation. The median penalty in those inspections was about $19,900 as first issued, and eight topped $50,000. About a third of those cases are still open and may change.

3. Scaffolds and aerial lifts. For inspections opened in 2025, scaffold and aerial lift citations rose to 125 items, from 90 in 2023 and 65 in 2024, even though fewer inspections were opened. 2025 counts may still grow as citations are issued. Scaffolds are the second most-cited standard locally for trades other than roofing.

4. Struck-by equipment. In OSHA accident records linked to these inspections (2023 through February 2025), 15 of 36 fatality records involved being struck by or caught in equipment or objects, such as loaders, rollers, dozers, falling materials, and motor vehicles. 17 involved falls.

5. Paperwork counts too. Across the area, OSHA issued 41 citations for not reporting a death or serious injury on time, 36 for missed electronic filing of the injury summary (Form 300A), and 146 for missing written fall protection training records.

What OSHA cites most around here

  1. Fall protection (858 citations; residential fall protection alone was 706)
  2. Ladders (396)
  3. Eye and face protection (277)
  4. Fall protection training and records (271)
  5. Scaffolds (236)

Trenching citations are less common, but they include some of the largest local penalties outside roofing (see pattern 1 above).

A note on heat: in this data we found almost no local heat-related fines. That doesn’t mean heat isn’t a risk. It’s still an important prevention topic for Florida crews, especially new workers in their first week.

Practical steps for your next job

  • Write it down. Keep a written fall protection plan and a trench and excavation plan for each job, and walk the crew through them.
  • Name a competent person for trenches and scaffolds: someone who inspects trenches daily and scaffolds before each shift, can spot hazards, and is authorized to take prompt corrective action.
  • Keep training records. OSHA requires a written fall protection training certification record with each worker’s name, the training date(s), and the signature of the trainer or the employer. Toolbox talk sign-in sheets help too.
  • Check ladders and scaffolds before use: ladder rails 3 feet above the landing, guardrails, planking, and tie-off in aerial lifts.
  • Control equipment around people: spotters, backup alarms, seatbelts on equipment with rollover protection, and clear walk zones.
  • Know your reporting deadlines. Report a work-related fatality within 8 hours, and an in-patient hospitalization, amputation, or loss of an eye within 24 hours (osha.gov/report or 1-800-321-OSHA).
  • File your Form 300A electronically by March 2 each year if a construction establishment had 20 or more employees at any time during the prior year. Larger establishments may have added filing duties under 29 CFR 1904.41.
  • Fix hazards fast and document it. Abatement records show what you corrected and when. In closed local cases, final penalties totaled about 29% less than first issued, but every case is different, and the data doesn’t show why any penalty changed. Talk with an attorney about any citation.

Where to get help

USF SafetyFlorida, Florida’s OSHA On-Site Consultation Program, offers complimentary, confidential safety consultations, primarily for smaller businesses. OSHA says consultations are separate from enforcement, and employers commit to correcting serious hazards the consultant finds. Call 1-866-273-1105.

McGriff-Williams Insurance is an independent insurance agency in Gainesville, serving clients since 1983. For our workers’ comp clients, we offer audit support, a safety training platform, OSHA support, and access to live HR professionals. To talk through your safety program or training records, call a licensed member of our team at (352) 371-7977.


About this data: Counts come from OSHA’s public inspection and violation data for federal OSHA inspections of construction employers (NAICS 23) opened January 2023 through September 17, 2026 (the latest date in files downloaded October 15 and 16, 2026), at sites within about 120 miles of Gainesville, measured straight-line from ZIP code centers. Sites whose ZIP code couldn’t be matched aren’t included, and the data doesn’t cover every job site or any state or local enforcement. “As first issued” totals include items OSHA later deleted. Current penalties reflect informal settlements, contests and final orders recorded so far, and open or contested cases may still change. OSHA can take up to six months to issue citations, so recent numbers may be understated. Fatality records run only through February 2025, and one event can appear under more than one employer. Roofing contractors are included (about 29% of inspections and 46% of first-issued penalties). General information only, not legal advice.

Sources

  • OSHA/DOL enforcement data (inspection, violation and accident datasets): https://data.dol.gov ; bulk files used: https://dataportal.dol.gov/datasets/10334 and https://data.dol.gov/data-catalog/OSHA/violation/OSHA_violation.zip (downloaded Oct 15 and 16, 2026)
  • OSHA penalties: https://www.osha.gov/penalties
  • OSHA national emphasis programs (falls, 2023 release; trenching and excavation, CPL 02-00-161): https://www.osha.gov/news/newsreleases/osha-national-news-release/20230501 ; https://www.osha.gov/enforcement/directives/nep
  • OSHA Florida area offices: https://www.osha.gov/contactus/bystate/fl/areaoffice
  • Severe-injury reporting (29 CFR 1904.39): https://www.osha.gov/report
  • Electronic 300A submission and covered industries: https://www.osha.gov/laws-regs/regulations/standardnumber/1904/1904.41 ; https://www.osha.gov/recordkeeping/naics-codes-electronic-submission
  • USF SafetyFlorida consultation: https://health.usf.edu/publichealth/research/cohpe/safetyflorida/
  • OSHA On-Site Consultation Program: https://www.osha.gov/consultation
  • Fall protection training certification (29 CFR 1926.503): https://www.osha.gov/laws-regs/regulations/standardnumber/1926/1926.503


Auto Insurance Tips for Rain, Storms, and Tropical Weather

Driving in states known for beautiful weather, like Florida and Louisana, brings a unique set of challenges often centered around sudden, intense rain and tropical storms. From dangerous hydroplaning conditions to widespread flooding, these events pose a significant risk to your vehicle and safety. While preparing for localized threats is crucial, understanding how your auto insurance protects you during these unpredictable, high-water months is equally important. Taking proactive steps now may save you from a major financial hit when the skies open up.

🚗 Preparing Your Vehicle for Wet and Stormy Roads

Warm weather means you won’t worry about antifreeze, but you must focus on the components vital for traction and visibility in heavy downpours.

  • Tires are Key: Inspect your tread depth regularly. Even a small drop in tread significantly increases your risk of hydroplaning on rain-slicked roads. Replace tires before they hit the minimum legal depth. Also, ensure your tire pressure is correct—improperly inflated tires lose contact with the road more easily in standing water.
  • Wiper Blade Health: In torrential rain, your visibility depends entirely on your wipers. Replace your wiper blades at least once a year or as soon as you notice streaking or chattering. Top off your windshield washer fluid frequently.
  • Brake Inspection: Heavy rain and flash flooding increase your stopping distance. Have your brakes inspected for wear to ensure maximum stopping power when you need it most.
  • Battery Check: The high heat and humidity found in warmer states can actually stress your car’s battery and reduce its life. Have your battery tested periodically to prevent a sudden breakdown during a storm.

🧰 Don’t Drive Without a Year-Round Emergency Kit

While snow gear isn’t needed, having a comprehensive kit is essential for situations like being stranded in traffic due to flooding or encountering road debris.

Your must-have emergency list includes:

  • Visibility and Safety: A quality first-aid kit, brightly colored flares or reflective triangles, and a flashlight with extra batteries (essential during power outages or night storms).
  • Communication: A fully charged cell phone and a portable charger are vital for calling for assistance or checking weather updates.
  • Tools: Basic tools, jumper cables, and a small air pump for tires.
  • Sustenance: Non-perishable food and bottled water, especially if you are traveling during hurricane season.

🛡️ What Your Auto Insurance Covers in Stormy Weather

Understanding your policy is key to feeling secure with your coverage, especially when the threat of tropical storms and flooding is present. Your auto insurance protects you from common weather-related damage, but only if you have the right coverage.

  • Comprehensive Coverage is Crucial: This is your primary defense against weather damage. Comprehensive Coverage handles damage to your vehicle resulting from “non-collision” events. This is highly relevant in warm, coastal states for:
    • Flood Damage: If your car is damaged by rising floodwater or standing water.
    • Wind Damage: If a tree, sign, or debris falls on your car during a tropical storm or hurricane.
    • Hail: If your car is damaged by hailstones.
    • It also covers theft, vandalism, and accidents with animals.
  • Collision Coverage: This pays for damage to your vehicle if you are involved in an accident with another car or object. If you hydroplane on a wet road and hit a guardrail or another vehicle, your Collision Coverage helps pay for your car’s repairs, minus your deductible.
  • Liability Coverage: Mandatory in almost every state, this protects you financially if you are at fault for an accident. If heavy rain causes you to lose control and damage someone else’s vehicle (Property Damage) or injure another person (Bodily Injury), your liability coverage steps in to cover those costs.

Actionable Tip: Flood damage is not covered by Collision—it is covered exclusively by Comprehensive Coverage. If you live in a flood-prone area, ensure you have this coverage and that your limits are adequate.

🌊 Stay Protected Year-Round

In states where the biggest threats come from the sky, not the thermometer, driving safely means respecting the power of rain and tropical systems. Your best strategy is a combination of attentive driving, ensuring your tires and wipers are always in top condition, and, most importantly, confirming you have robust Comprehensive Coverage in place. Take a moment today to review your policy and your deductible with you us. By being prepared for sudden downpours and strong winds, you become confident that you can navigate the roads with confidence and financial security, no matter what the forecast brings.

A Season of Thanks: Why We’re Grateful for Our Clients (and How to Protect What You’re Thankful For)

As the holiday season approaches, it’s a time to reflect on the blessings of the past year and express gratitude for the relationships that enrich our lives. At our agency, we’re especially thankful for the trust and confidence our clients place in us. It’s not just about policies; it’s about the privilege of safeguarding what matters most to you – your home, your business, your family. This Thanksgiving, we pause to honor the partnerships we’ve built and the opportunity to serve you.

Gratitude for Our Clients

Every policy we write represents a relationship, not just a transaction. We’re honored to help safeguard homes, cars, businesses, and families. Your trust in us is the foundation of our work, and we don’t take that lightly.

Protect What You’re Thankful For

Take time to review your coverage as the year winds down. Whether it’s a new car, home improvement, or business growth, make sure your policies reflect your current life. Life changes, and so should your protection.

Looking Ahead with Appreciation

We’re grateful for another year of connection, growth, and community. From our team to yours — we wish you a happy, safe, and heart-filled Thanksgiving. Because gratitude isn’t just a feeling — it’s an action. Protecting what matters most is one way to show it.

In this season of thankfulness, we recognize that our success is intertwined with the trust and loyalty of our clients. Your continued support inspires us to strive for excellence in every service we provide. As we look ahead, we remain committed to protecting what you value most for you and your loved ones. From our team to yours, we wish you a joyful, safe, and heartwarming Thanksgiving. May it be filled with cherished moments and lasting memories.

Football Season = Tailgate Safety

Before kickoff, give your insurance a pre-game check.

It’s that time of year again — crisp fall air, rivalries heating up, and the smell of burgers on the grill in stadium parking lots and backyards everywhere. Tailgating and football parties are some of the best traditions of the season. But while you’re planning the snacks and setting up that big-screen TV, it’s worth asking: is your insurance ready for game day, too?

Auto Insurance & Tailgating

Many tailgates happen in stadium parking lots. If your vehicle is damaged — whether it’s a door ding from another fan or a fender bender leaving the lot — your auto policy can help. Comprehensive coverage also comes into play if your grill or cooler scratches the paint, or worse, if an accident happens while hauling your gear. Pro tip: Double-check your liability limits before the season starts — it’s a simple pre-game warm-up that can save you headaches later.

Homeowners Insurance & Backyard Parties

Not heading to the stadium? Backyard football parties are just as popular. If a guest trips over an extension cord or slips on a wet deck, you could be held liable. That’s where your homeowners (or renters) insurance liability coverage comes in. And yes — if you’ve invested in that giant outdoor TV or sound system, make sure it’s covered under your personal property limits.

Umbrella Coverage = Extra Protection

For true peace of mind, umbrella insurance adds an extra layer of protection above your auto or home policies. If a serious accident happens at your tailgate or party, and the costs go beyond your standard liability limits, an umbrella policy helps cover the difference. Think of it as your insurance defensive line.

Quick Tailgate Safety Tips

– Keep walkways clear of cords, coolers, and chairs.
– Grill safely — never leave it unattended.
– Have a designated driver plan before kickoff.
– Know your coverage before the party starts.

Game Plan Recap

Football season is about fun, food, and friends — not fumbles with your insurance. A quick review of your auto, homeowners, and umbrella policies ensures you’re covered, no matter what game day brings.

Before kickoff, give your insurance a pre-game check and enjoy the season with confidence.

How to Help Prepare for a Hurricane

Your level of preparation before a hurricane can have a significant impact on how well you weather the storm and how quickly you recover from it. Consider preparing your home, inside and out, long before a storm is in the forecast. In the end, you can never be too prepared when it comes to protecting your loved ones and your property from hurricanes and other extreme weather events.

Know the forecast

You may hear the terms “Hurricane Watch” and “Hurricane Warning” in your local forecast. Understanding the difference between them is essential to helping you prepare for a hurricane. As soon as a Hurricane Watch or Hurricane Warning is forecast for your area, it is important, depending on the type of alert, to immediately begin or complete your preparations.

A Hurricane Watch means hurricane conditions are possible within 48 hours. Begin stocking up on emergency supplies in the event a warning is issued. If you live in a coastal area, you also should be prepared to evacuate.

A Hurricane Warning is more serious. Hurricane-force winds (74 mph or higher) are expected to hit your area within 36 hours. Seek shelter or evacuate if notified to do so.

General hurricane preparation tips

  • Prepare a survival kit that includes items such as water, nonperishable food and medications for everyone, including your pets; a portable radio; flashlights; batteries; and battery chargers for your cellphones and other portable electronic devices, which can be powered by your car.
  • Plan your evacuation route and leave as soon as an evacuation order is issued. Also, fuel up your car before you leave.
  • Build a content inventory of the items in your home or at your business.
  • Secure all outdoor objects or move them inside. Close your home’s storm shutters and board up windows and glass doors as appropriate.
  • If possible, bring in gas or charcoal grills, but do not use them indoors. Also, do not store propane tanks inside the house or garage. Chain propane tanks in an upright position to a secure object away from your home.
  • Secure your boat or move it to a safer place.
  • Fill your emergency generator fuel tank, if you have one, and have spare fuel on hand. Store generator fuel in an approved container in a garage or shed, away from open flames, heat sources and appliances such as natural gas appliances.

Keep Track with Our Emergency Checklist

Five tips to help prepare your home for a hurricane

  1. Help avoid water damage

Heavy rains have the potential to cause significant water damage. These tips can help you prepare your home.

  • Close and lock all windows and doors and remove any window air conditioners.
  • Remove valuable items from your basement or elevate them off of the floor.
  • Clear debris from exterior drains and gutters.
  • Repair damaged gutters and downspouts to make sure water can drain away from your foundation.
  • Check your sump pump and the battery backup to confirm they are working properly.
  1. Monitor your trees

In a powerful windstorm, trees can be a hazard. Broken limbs or fallen trees – even uprooted shrubbery – could damage your home and fences, or your neighbor’s property.

Routinely maintain the trees around your home:

  • Prune tree limbs within 10 feet of your home.
  • Check for cracking or splitting in trees.
  • Remove dead limbs and weakened trees.
  1. Roofs, doors, windows and skylights

It is important to keep wall openings such as doors, windows and skylights protected. The roof, doors and windows of your house are especially vulnerable to wind damage. When houses are exposed to hurricane-force winds, roofs are most susceptible to damage, followed by walls and openings such as skylights.

Strengthen doors and windows by:

  • Installing reinforcing bolt kits at the top and bottom of doors.
  • Reinforcing garage doors.
  • Installing storm shutters over windows.
  1. Secure outdoor Items

If you live in an area that experiences high winds, outdoor items around your property that are not properly anchored can become airborne and cause damage.

  • If high winds are expected in your area, move as many outdoor items indoors well before the high winds arrive. As mentioned earlier, do not store propane tanks in your home or garage.
  • Adequately secure any remaining outdoor items that cannot be safely moved to protected areas.
  1. Strengthen your exterior structure

During a windstorm, wind forces are carried from the roof down to the exterior walls and then to the foundation. Homes can be damaged when wind and wind-driven water get under the building’s exterior walls if proper controls are not in place.

Strengthen exteriors by employing a contractor to:

  • Install hurricane straps to reinforce roof-to-wall and wall-to-foundation connections.
  • Retrofit soffits to help ensure they remain in place in high winds.
  • Properly brace roof trusses.

The effort and time you invest in hurricane preparedness can make all the difference—not only in safeguarding lives, but also in limiting damage and accelerating recovery. From understanding local alerts to stocking emergency supplies and reinforcing your home well in advance, each proactive step builds resilience. Whether you evacuate or shelter in place, early and thorough preparation helps protect your loved ones and property from the worst of what a storm can bring. You truly can’t be too prepared when protecting what matters most. Stay ready, stay informed, and above all, prioritize safety long before the skies darken.

Source