
Charging Batteries in the Garage: Fire Safety Tips for Carts, E-Bikes and Tools

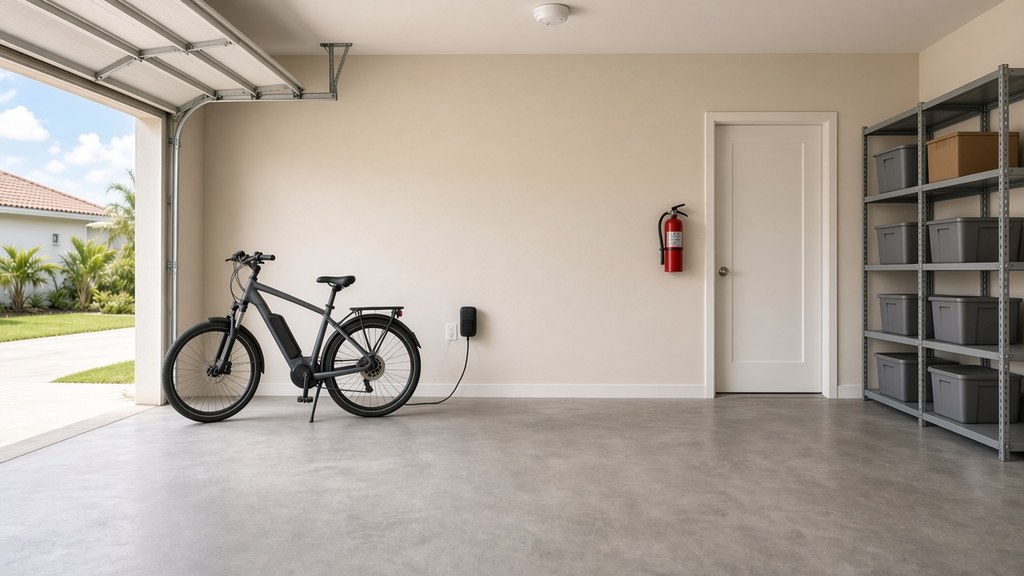
An e-bike charging on the bare concrete floor of a tidy home garage with the overhead door open, its charger plugged into a wall outlet, with a ceiling alarm, a fire extinguisher beside the closed door into the house and shelves of storage bins along the side wall.

For many Florida households, the garage is where everything gets plugged in: the golf cart, the e-bike, the kids’ scooters, the mower and a shelf of power tool batteries. That makes it worth a few minutes to think about how you charge them. The CFO and State Fire Marshal’s office notes that lithium-ion batteries in devices like power tools, e-bikes and e-scooters can overheat, start a fire or explode if they’re misused, damaged or charged improperly. The U.S. Fire Administration (USFA) says garage fires tend to spread farther and cause more injuries and dollar loss than fires that start in all other areas of the home.

Here’s what public fire safety agencies recommend, and a few insurance questions to ask while you’re at it.

1. Know the warning signs

Fire safety agencies describe the same set of red flags. Stop using or charging a battery or device if it:

  • Feels very hot
  • Swells, bulges or changes shape
  • Has a strange odor or changes color
  • Leaks or smokes
  • Makes hissing, popping or other odd sounds

UL’s Fire Safety Research Institute (FSRI) adds that white or gray wispy smoke means there’s an immediate danger of fire, and that from the first sign of a problem you could have less than a minute to escape a lithium-ion battery fire.

2. Charge with the right equipment

  • Use the charger that came with the device, or one the manufacturer approves. The U.S. Consumer Product Safety Commission (CPSC) warns against chargers sold as “universal” or as suitable for a general category of e-bikes or scooters. They may fit but still be incompatible with your battery, which can cause a fire.
  • Use the battery made for the device. CPSC advises using only replacement battery packs the device’s manufacturer confirms are suitable, and never a pack that’s been modified or rebuilt with used cells.
  • Look for safety certification. NFPA recommends products listed by a nationally recognized testing laboratory. CPSC has called on manufacturers to certify e-bikes to UL 2849, the safety standard for e-bike electrical systems, and e-scooters, hoverboards and similar devices to UL 2272, the standard for electrical systems for personal e-mobility devices. Because these standards cover the device’s electrical system as a whole, look for a certification mark on the device itself, not just on a separate battery or charger.

3. Charge in the right place, and stay with it

  • Outside when you can. NFPA and the State Fire Marshal’s office recommend charging large items like e-bikes, scooters and power tools outside when possible, and never where they’d block an exit.
  • On a hard surface. Charge on a hard, flat surface such as a bare concrete floor or workbench, not on carpet, cushions or a pile of rags. Soft surfaces can trap heat.
  • Away from things that burn. NFPA says to store batteries away from anything that can catch fire. USFA suggests keeping gasoline, oil, paint, propane and varnish in a shed away from the house, and keeping items that can burn on shelves away from appliances.
  • Plug straight into the wall. USFA recommends plugging only one charging appliance into an outlet and not using an extension cord to charge.
  • Be there. CPSC says to always be present while charging e-bikes and scooters and never to charge them while you’re asleep or away from home. FSRI also advises against charging larger devices overnight.
  • Unplug when it’s full. Leaving a device plugged in can add heat and stress to the battery.
  • Mind the heat. NFPA advises not charging lithium-ion batteries above 105°F or below 32°F. A closed garage in a Florida afternoon can get hot, so check the temperature, and your manual, before you plug in.

4. Golf carts: ventilation matters

Golf carts can use lead-acid, lithium-ion or AGM batteries, so start with the cart’s manual and the battery maker’s charging instructions. Lead-acid batteries give off hydrogen gas as they charge, and the U.S. Occupational Safety and Health Administration (OSHA) warns that it can explode if it builds up in a closed space. Palm Beach County Fire Rescue warns that overcharging, or poorly maintained batteries, can release hydrogen gas, which is highly flammable, and that charging in a garage with the door and windows closed is dangerous. Its advice:

  • Charge the cart outside, at least 5 feet from the house, if you can.
  • If you charge in the garage, keep the garage door or windows open, charge only when you’re home and awake, and unplug as soon as the batteries are full. Don’t charge overnight, and don’t count on a “smart” charger to shut itself off.
  • For lead-acid batteries, check water levels often.
  • Plug the cart directly into a GFCI outlet, and keep working carbon monoxide alarms in the home. Hydrogen from charging carts can set off CO alarms.
  • If a CO alarm sounds, get out and call 911. Leave through a side door or open the garage door by hand. Don’t flip light switches or press the garage door opener, which can ignite the gas.

5. Mowers, power tools and other batteries

Lithium-ion batteries in cordless mowers, trimmers and power tools follow the same rules: the right charger, a hard surface, nothing flammable nearby, and unplugged when full. When a battery is worn out or damaged, don’t put it in the trash or your curbside recycling bin. CPSC, NFPA and FSRI all say to take it to a battery recycling or household hazardous waste location instead. NFPA notes that many stores that sell large quantities of lithium-ion batteries have recycling programs that take them back. Don’t charge a battery that shows signs of damage. If a battery or device has been damaged by water, NFPA suggests asking your local fire department, waste department or the manufacturer how to handle and dispose of it.

6. Set up the garage to warn you and slow a fire

  • A heat alarm, not a smoke alarm. USFA says smoke alarms aren’t designed for garages, where changes in temperature and humidity, dust and fumes can set them off. It recommends a heat alarm rated for 175 to 250°F that’s hard-wired with battery backup, interconnected with your home’s smoke alarms and installed by a qualified electrician.
  • Working smoke alarms inside the home and a home fire escape plan everyone knows.
  • A fire-rated door between the garage and the house. USFA recommends a 20-minute fire-rated door that closes and latches on its own. Keep it closed.
  • A fire extinguisher, used only in the right situation. USFA notes that multipurpose “A-B-C” extinguishers cover most types of home fires. Use one only when everyone in the home has been alerted, someone has called 911, you’re physically able to use it, the fire is small and contained to one object, you’re safe from the smoke and you have a clear way out. If you’re unsure, leave. Young children and older adults shouldn’t use fire extinguishers. If a lithium-ion battery is smoking or on fire, follow FSRI’s advice in the next section: get out and call 911.

7. If a battery starts smoking or catches fire

Get out. FSRI’s advice is to follow your home fire escape plan, leave immediately and call 911. FSRI’s research also shows that closing doors helps slow the spread of fire, so close doors behind you if you can on your way out. If you notice a warning sign before there’s any smoke or fire, and it’s safe to do so, NFPA suggests moving the device away from anything that can catch fire and calling 911.

8. Insurance questions worth asking

Safety habits come first, but it’s also a good time to look at your coverage.

  • Fire is typically a covered cause of loss. Florida’s Department of Financial Services lists fire and smoke among the perils homeowners policies may include. Whether a particular loss is covered is subject to your own policy’s terms, including its wording, limits, deductibles and exclusions.
  • Document what’s in the garage. The Department of Financial Services recommends a room-by-room home inventory that includes the garage, with photos or video, serial numbers, purchase dates and prices, updated at least once a year. Keep receipts for carts, e-bikes, mowers and tools, and store all of these records in a safe, dry place.
  • Check how your golf cart is covered. Many homeowners policies limit or exclude coverage for motorized vehicles, and golf carts often fall into that category, both for damage to the cart and for liability. Whether your policy applies can depend on its wording and on how and where the cart is used, such as on a golf course, around your neighborhood or on public roads. Florida law defines a golf cart as a vehicle made for golf course use that can’t go faster than 20 mph. A low-speed vehicle, with a top speed over 20 and up to 25 mph, must be registered, titled and insured to be driven on the road. Depending on your policy and how you use the cart, you may need an endorsement or a separate policy, and either one has its own terms and exclusions. For example, it may not cover a battery or charger that wears out or fails on its own. E-bikes and e-scooters can raise similar questions, even though Florida law treats e-bikes much like bicycles. Before you assume your home policy applies, a licensed member of our team can review how it treats your cart and other battery-powered equipment.

FAQ

Is it safe to charge an e-bike in the garage?
Fire safety agencies recommend charging e-bikes and scooters outside when possible. If you charge in the garage, use the manufacturer’s charger, charge on a hard surface away from anything flammable and away from exits, stay home and awake while it charges, and unplug it when it’s full.

Should I put a smoke alarm in my garage?
USFA recommends a heat alarm rather than a smoke alarm in the garage, interconnected with your home’s smoke alarms, because garage conditions can trigger false smoke alarms.

Does my homeowners policy cover my golf cart?
It depends on your policy and on how and where you use the cart. Many homeowners policies limit or exclude motorized vehicles, and in Florida, a low-speed vehicle (top speed over 20 and up to 25 mph) must be registered, titled and insured to be driven on the road. Some owners need an endorsement or a separate policy, which has its own terms and exclusions. A licensed member of our team can review how your current policy treats your cart.

Let’s review your coverage

McGriff-Williams Insurance is an independent agency in Gainesville since 1983. If you keep a golf cart, e-bikes or other battery-powered equipment at home, a licensed member of our team can review your current home and auto coverage with you, including how it treats them. Call (352) 371-7977 or contact us.

This article is general information, not a statement of coverage. Your policy’s terms, conditions and endorsements control. Coverage options vary by company and are subject to underwriting and availability. Safety tips are general; always follow your device manufacturer’s instructions and your local fire officials. Information is as of October 22, 2026.

Sources

  • Florida Department of Financial Services, “Chief Financial Officer and State Fire Marshal Blaise Ingoglia Highlights 2026 Fire Prevention Week, ‘Charge into Fire Safety. Safe Charging is a Superpower'” (Oct 5, 2026), accessed Oct 22, 2026: https://www.myfloridacfo.com/news/pressreleases/press-release-details/2026/10/05/chief-financial-officer-and-state-fire-marshal-blaise-ingoglia-highlights-2026-fire-prevention-week---charge-into-fire-safety.-safe-charging-is-a-superpower
  • U.S. Consumer Product Safety Commission, “Micromobility: E-Bikes, E-Scooters and Hoverboards,” accessed Oct 22, 2026: https://www.cpsc.gov/Safety-Education/Safety-Education-Centers/Micromobility-Information-Center
  • U.S. Consumer Product Safety Commission, “CPSC Urges Consumers to Not Buy or Use ‘Universal’ Chargers with Micromobility Products Due to Fire Hazard” (Sept 5, 2024), accessed Oct 22, 2026: https://www.cpsc.gov/Newsroom/News-Releases/2024/CPSC-Urges-Consumers-to-Not-Buy-or-Use-Universal-Chargers-with-Micromobility-Products-Due-to-Fire-Hazard
  • U.S. Consumer Product Safety Commission, “CPSC Calls on Manufacturers to Comply with Safety Standards for Battery-Powered Products to Reduce the Risk of Injury and Death” (Dec 20, 2022), accessed Oct 22, 2026: https://www.cpsc.gov/Newsroom/News-Releases/2023/CPSC-Calls-on-Manufacturers-to-Comply-with-Safety-Standards-for-Battery-Powered-Products-to-Reduce-the-Risk-of-Injury-and-Death
  • NFPA, “Lithium-Ion Battery Safety,” accessed Oct 22, 2026: https://www.nfpa.org/education-and-research/energy-transition/lithium-ion-batteries
  • NFPA, Fire Prevention Week 2026 tip sheet, “Safe Charging Is a Superpower,” accessed Oct 22, 2026: https://www.nfpa.org/-/media/Project/Storefront/Catalog/Files/Fire-Prevention-Week/2026/FPW26_Tip-Sheet.pdf
  • NFPA, “Lithium-Ion Battery Safety” tip sheet, accessed Oct 22, 2026: https://content.nfpa.org/-/media/project/storefront/catalog/files/safety-tip-sheets/lithiumionbatterysafetytips.pdf
  • UL Research Institutes’ Fire Safety Research Institute, “Take C.H.A.R.G.E. of Battery Safety,” accessed Oct 22, 2026: https://batteryfiresafety.org/
  • U.S. Fire Administration, “Basement and Garage Fire Safety” (last reviewed April 1, 2023), accessed Oct 22, 2026: https://www.usfa.fema.gov/prevention/home-fires/prevent-fires/basement-and-garage/
  • U.S. Fire Administration, “Heat Alarms” (last reviewed April 1, 2023), accessed Oct 22, 2026: https://www.usfa.fema.gov/prevention/home-fires/prepare-for-fire/heat-alarms/
  • U.S. Fire Administration, “Choosing and Using Fire Extinguishers” (last reviewed April 1, 2023), accessed Oct 22, 2026: https://www.usfa.fema.gov/prevention/home-fires/prepare-for-fire/fire-extinguishers/
  • UL Research Institutes’ Fire Safety Research Institute, “Close Before You Doze,” accessed Oct 22, 2026: https://closeyourdoor.org/
  • U.S. Occupational Safety and Health Administration, “Powered Industrial Trucks eTool: Power Sources – Electric,” accessed Oct 22, 2026: https://www.osha.gov/etools/powered-industrial-trucks/types-fundamentals/power-sources/electrical
  • Palm Beach County Fire Rescue, “Golf Cart Safety,” accessed Oct 22, 2026: https://discover.pbc.gov/pbcfr/CRRD/Pages/Golf-Cart-Safety.aspx
  • Florida Department of Financial Services, “Homeowners’ Insurance: A Toolkit for Consumers” (perils list p. 4; home inventory pp. 19–20), accessed Oct 22, 2026: https://www.myfloridacfo.com/docs-sf/consumer-services-libraries/consumerservices-documents/understanding-coverage/consumer-guides/english---homeowners-insurance-toolkit.pdf
  • Florida Statutes s. 316.2122 (low-speed vehicles) and s. 320.01(22) and (41) (definitions), accessed Oct 22, 2026: https://www.flsenate.gov/Laws/Statutes/2026/316.2122 and https://www.flsenate.gov/Laws/Statutes/2026/320.01
  • Florida Statutes s. 316.20655 (electric bicycles), accessed Oct 22, 2026: https://www.flsenate.gov/Laws/Statutes/2026/316.20655
Year-End Insurance Checklist for Florida Contractors

From the I-75 corridor in Marion County to the job sites around Jacksonville and St. Johns County, North Central and Northeast Florida contractors have had a busy year. Busy years are also when insurance paperwork slips: a sub’s certificate expires, an exemption runs out, or payroll outgrows the policy estimate.

Before you start bidding 2027 work, here’s a practical checklist for general contractors, site work and underground utility contractors, electricians, HVAC and plumbing contractors, and concrete, fencing and pool companies.

1. Know Florida’s Construction Rule for Workers’ Comp

Florida treats construction differently. Outside construction, workers’ compensation generally applies once a business has four or more employees. In the construction industry, it applies once you have one employee (section 440.02, Florida Statutes). Every contractor and subcontractor doing construction work in Florida has to secure and maintain coverage for its employees (section 440.10).

If your crew or your services grew this year, make sure your policy reflects it.

2. Check Officer Exemption Expiration Dates

Many contractors run as corporations or LLCs with officers who have elected to be exempt from workers’ comp. A few Florida rules to keep in mind:

  • In construction, no more than three officers of a corporation (or group of affiliated corporations) can be exempt. Each must own at least 10% of the company and be listed as an officer with the Florida Division of Corporations. For LLCs, the member must own at least 10%.
  • A construction exemption certificate is valid for two years and expires at midnight on the date shown. The Florida Department of Financial Services (DFS) sends a notice at least 60 days before it expires.
  • Applications and renewals are filed online with the DFS Division of Workers’ Compensation, carry a $50 fee, and require a short online coverage-and-compliance tutorial.
  • An exemption applies only to the officer named on it, for the companies listed on it. It is not a contractor’s license.

To do: pull up each officer’s certificate, note the expiration date and put a renewal reminder on the calendar.

3. Get Your Subcontractor Certificates in Order

This is where we see the most surprises at audit time.

Under Florida law, when a contractor sublets work, the contractor is responsible for workers’ comp for the subcontractor’s employees on that job, unless the subcontractor has its own coverage (section 440.10). The law also says the contractor must require subs to show proof of workers’ comp, and an exempt officer must give the contractor a copy of the exemption certificate.

A simple routine helps:

  • Collect a certificate of insurance (COI) for workers’ comp and general liability from every sub before they start work, and track the expiration dates.
  • Verify workers’ comp coverage and exemptions on the DFS Proof of Coverage database. It takes about a minute.
  • Keep copies organized by sub and by job. Your auditor will ask for them.
  • Check your contracts. If you require subs to name you as an additional insured or carry certain limits, confirm their certificates show it.

Uninsured subs can show up as added premium at audit, and worse, as a claim on your own policy.

4. Prepare for Your Premium Audit

Workers’ comp and many general liability policies start with an estimate of your payroll, sales or subcontracted costs. After the policy year ends, the carrier audits your actual numbers, usually every year for contractors (and on-site for larger policies), and adjusts the premium up or down.

You can make audits smoother, and avoid surprises, by having these ready:

  • Payroll records by employee and by job duty (class code). If someone works in more than one trade, keep time records that show hours in each. Without them, the auditor can put all of that person’s pay in the highest-rated class.
  • Overtime records that show the overtime premium separately (the extra “half” is left out of workers’ comp payroll only if your records break it out), plus officer payroll and copies of any officer exemptions.
  • A list of every subcontractor you paid, with amounts and their certificates. Make sure each certificate or exemption was in force on the dates the sub worked for you. If the auditor can’t get access to your records, Florida lets the carrier charge up to three times your estimated annual premium.
  • Notes on any change in operations: new services, new counties, larger projects.

If payroll has grown a lot since your policy started, call us before the audit. Updating your estimate mid-term spreads the extra premium across your remaining payments, so you won’t face one large bill at audit. It also keeps your certificates and limits in line with your real size.

5. Look Ahead to 2027 Bids

Before the new year’s contracts land on your desk, review:

6. Don’t Forget the Weather

Hurricane season runs through November 30, and Hurricane Isaias was a reminder that storms can arrive late. Review your jobsite storm plan: securing materials and equipment, protecting partially completed work, and knowing how your builders risk and equipment policies handle named-storm deductibles.

Why It Matters

DFS enforces workers’ comp coverage in construction, and a business found without the required coverage can face a stop-work order and penalties (section 440.107). A well-organized file also keeps your premium accurate and your projects moving.

Let’s Review Your Program Before Year-End

McGriff-Williams has worked with Florida contractors since 1983. We’re an independent agency, so we compare options from multiple insurance companies for workers’ comp, general liability, auto, equipment, builders risk and umbrella coverage. Then we help you stay organized all year: certificates, audits, exemptions and renewals. Call us at (352) 371-7977 or request a business insurance review. You can also learn more about our workers’ compensation and business insurance services.


General information, not legal advice. Coverage depends on the policy issued, its terms and underwriting. Florida workers’ compensation rules are set by Chapter 440, Florida Statutes, and DFS rules; confirm your situation with your agent, carrier or the DFS Division of Workers’ Compensation. McGriff-Williams Insurance is an independent insurance agency licensed in Florida. Information current as of October 2026.

Protecting Trading Cards at Home, in the Mail and in the Shop

Graded trading cards in clear protective cases on a desk beside a padded box and a magnifying loupe.

On October 13, 2026, a FedEx driver found that two pallets of graded trading cards, including sports and Pokémon cards, and some packages from a third pallet had been taken from his truck, which was parked at or near PSA’s facility in Santa Ana, California, according to police and news reports. The initial estimated value was $963,000, and police have said the final figure may be higher. These details are as reported, and the facts are still developing. According to the Los Angeles Times, the cards had been graded and were set to be returned to their owners, and PSA told customers in a letter quoted by the LA Times that a FedEx vehicle transporting PSA orders was burglarized “after leaving our PSA facility in Southern California.” FreightWaves reported on October 20 that police were still working to determine when and where the theft happened, and as of October 21, 2026, no arrests had been reported. PSA said in a public statement that it has deactivated the stolen cards’ certificates and is arranging compensation for affected customers based on fair market value.

It’s a reminder that cards spend time in many places: at home, at a show, in the mail and at a grading company. Each can be covered differently, or not at all.

1. Collectors: at home, traveling and at card shows

Keep a record of what you own. Front and back photos, certificate numbers, receipts and dated sale comparisons make a claim much easier to document.

Think about where the cards live. The FDIC notes that safe deposit box contents aren’t covered by FDIC deposit insurance and that banks generally don’t insure them, so ask your agent about coverage for valuables kept there.

At shows and while traveling: keep high-value cards with you rather than in a parked car, don’t post your location or haul in real time, and check whether your policy covers cards away from home.

2. Shipping: what “declared value” does and doesn’t do

Carrier limits for collectibles can be low. For example, FedEx’s 2026 Service Guide (effective Jan. 5, 2026, updated Sept. 11, 2026; checked Oct. 21, 2026) limits its liability to $100 per package unless a higher value is declared, up to $50,000 per package for most U.S. services. But shipments containing “collector’s items such as coins, stamps, sports cards, souvenirs, and memorabilia” are limited to a maximum declared value of $1,000, so a card worth $5,000 can’t be declared for more than $1,000. The same guide caps anything shipped in a FedEx Envelope or Pak at $500.

Declared value isn’t insurance. FedEx’s terms say so directly, and the shipper must prove actual damages. UPS and the U.S. Postal Service publish their own limits, options and lists of items they won’t accept. These terms change, so check the carrier’s current rules before you ship.

A grading company covers only part of the trip. Under PSA’s published terms (updated April 22, 2026), for example, the customer “bear[s] the sole cost and risk” of loss on the way in, even with a PSA label, and PSA’s responsibility starts once the item is unpacked and confirmed received. While PSA has the card, compensation is capped at the lower of fair market value or the “Maximum Insured Value” of the service level you chose, so PSA advises choosing a level above the card’s expected value after grading. For the return trip, you can have PSA ship and insure the package, buy your own insurance, or use your own shipping account, which PSA doesn’t insure.

These are general published terms, and how they apply to any particular shipment, including the Santa Ana loss, hasn’t been made public. Your own policy may fill some of these gaps, depending on how it treats property in transit and held by others. Ask before you send cards out.

3. Card shop owners: inventory, customers’ cards and shipping

NBC Los Angeles reports that a handful of Southern California card shops have been targeted by break-ins in the past year. Things for shop owners to look for:

  • How inventory is valued. Some policies value stock at replacement cost, some at depreciated value, and some dealer policies at market value, often with a coinsurance requirement, so keep your insured amount in line with current values. Some also limit or exclude theft of categories like stamps or collectibles.
  • Security conditions. Some policies written for collectibles dealers set a lower theft limit for anything not locked in a safe, or require an alarm and safe, with coverage reduced if those conditions aren’t met. If you open a second location or move your safe, make sure the policy is updated to match.
  • Customers’ cards in your care. For consignments, holds and grading submissions, note that standard general liability policies exclude damage to personal property in your care, custody or control, and business property policies may include only a small amount for customers’ property unless you increase it. Bailee coverage or a “property of others” provision may help, along with written records of what you’re holding and for whom. Cards sent out for grading are away from your shop and in transit, so check whether your coverage follows them.
  • Shipping and shows. Inland marine coverage can be written to follow inventory in transit or at shows, usually with conditions. Some policies cover shipments well only when sent signature-required or by certain methods, and very little otherwise. There’s often a separate, lower limit for cards away from your shop, such as at a show, plus rules about unattended vehicles.
  • Theft and crime. Break-ins by outsiders are usually handled under your property policy’s theft coverage, if your policy includes theft, subject to the limits above. Some policies for collectibles dealers exclude employee theft, unexplained losses and shortages found only in an inventory count, so a separate crime policy may be needed. Crime policies have their own inventory-count exclusion, so keep item-level records. They can also cover theft of money from the premises or robbery.
  • Who’s named on the policy. Make sure the business that owns the inventory is named on the policy. If the stock belongs to your LLC but only you are named, that can complicate a claim.

4. Common homeowners gaps for collectors

A standard homeowners policy can cover a card collection as personal property, but there are common limits to know about. Many Florida homeowners policies are based on standard industry forms, and the points below describe how those forms commonly work. Your own policy may read differently, and its wording controls. Most policies set lower limits for categories such as money, coins, stamps, jewelry and business property. Trading cards usually aren’t a named category, but check how your policy treats them.

  • Business property limits. Homeowners policies usually set a much lower limit for property used mainly for a “business,” often $2,500 at home, with a separate, lower limit away from home that varies among Florida policies. Many policies define “business” broadly, including a trade done full-time, part-time or occasionally, and other paid activity once it earns more than a set amount in a year. If you buy and sell cards regularly, online, at shows or through consignment, the cards you hold for resale could be treated as business property, and a personal policy may limit or exclude them. It’s worth asking about business coverage for that part of your collection.
  • Mysterious disappearance. In a typical homeowners form, theft coverage includes property missing from a known place when it’s likely it was stolen. A card that simply goes missing, with nothing to suggest a theft, may not be covered.
  • Breakage. Most HO-3 policies cover personal property only for a list of named causes of loss, such as fire, smoke or theft. Accidentally dropping a slab isn’t on that list, so the damage may not be covered. Some policies offer broader “open perils” coverage for personal property, but even that can exclude breakage of fragile items. Your policy’s wording controls.
  • Theft away from home. Policies differ here. Some cover theft of your belongings away from home much as they would at home. Others cap it at a fraction of your personal property limit, and some Florida policies don’t cover theft away from your home at all. Policies can also set lower limits for property kept at a second home or in a storage unit. Check your policy before you take cards to a show, a hotel or a storage unit.
  • Replacement cost may not apply. Many policies offer replacement cost for personal property, but the standard replacement cost endorsement many policies use treats collector’s items and memorabilia whose age or history adds to their value as ineligible. Those are usually settled at actual cash value instead. Florida law also generally lets homeowners remove personal property (contents) coverage from their policy by signing a written statement, so it’s worth confirming that yours includes it.

Options that may help. Some policies let you add a scheduled personal property endorsement (sometimes called a floater) that lists valuable items or a collection individually, with its own amount of coverage. A floater can also be bought as a separate policy. These often cover more causes of loss than the homeowners policy itself, sometimes with no deductible. Not every policy allows scheduling, though, and not every insurer will schedule trading cards. Some floaters still exclude breakage of fragile items, or loss while shipping or on display.

A standalone collectibles policy is another option, and these value cards in different ways. Some use agreed value for listed items, meaning you and the insurer settle on an item’s value when it’s added, not after a loss. Others insure the whole collection on a blanket basis and pay market value at the time of a loss, often with no list required for lower-value items. Still others pay the lower of the listed amount or the item’s value at the time of loss, so ask which applies. Causes of loss, exclusions, eligibility and availability vary by company and by state. Card values change, so it’s worth reviewing your listed values and total limit regularly.

Questions to ask about collectibles coverage:

  • Is there a per-item limit on blanket coverage, and when should a card be listed individually?
  • What documentation or appraisal is needed, and how often should values be updated?
  • Are cards covered in the mail, at a show (including while displaying or selling) and while a grading company has them? Are there shipping-method or packaging rules?
  • Are accidental breakage and unexplained loss covered, and what deductible applies?

Damage from humidity, gradual deterioration or insects is commonly excluded, so storage conditions matter.

Let’s review your coverage

McGriff-Williams Insurance is an independent agency in Gainesville since 1983. Whether you collect, sell or run a card shop, a licensed member of our team can review your current home or business coverage with you, including how it treats your cards. Call (352) 371-7977 or contact us.

This article is general information, not a statement of coverage. Your policy’s terms, conditions and endorsements control. Coverage options vary by company and are subject to underwriting and availability. News details are as reported as of October 21, 2026 and may change.

Sources

  • NBC Los Angeles, “Trading cards worth nearly $1 million stolen from FedEx truck, PSA says” (Oct 19, 2026, updated Oct 20), accessed Oct 21, 2026: https://www.nbclosangeles.com/news/local/trading-cards-stolen-from-fedex-truck-psa/3958318/
  • FreightWaves, “Nearly $1M in Pokémon and sports cards vanish from FedEx truck, driver discovers missing lock” (Oct 20, 2026), accessed Oct 21, 2026: https://www.freightwaves.com/news/nearly-1m-in-pokemon-and-sports-cards-vanish-from-fedex-truck-driver-discovers-missing-lock
  • People, “Pokémon and Sports Cards Worth Nearly $1 Million Stolen from FedEx Truck, Police Say Value Could Be Higher” (Oct 20, 2026), accessed Oct 21, 2026: https://people.com/nearly-1-million-worth-of-pokemon-sports-cards-stolen-from-fedex-truck-california-police-say-12185357
  • Los Angeles Times, Steve Henson, “Almost $1 million in rare sports and Pokémon cards stolen from FedEx truck in Santa Ana” (Oct 20, 2026), accessed Oct 21, 2026: https://www.latimes.com/sports/story/2026-10-20/1-million-dollars-sports-pokemon-trading-cards-stolen-fedex-santa-ana
  • FedEx Service Guide 2026 (effective Jan. 5, 2026; updated Sept. 11, 2026), Terms and Conditions, “Declared value and limits of liability (not insurance coverage),” items A, B, C, E, G.11 and H, accessed Oct 21, 2026: https://www.fedex.com/content/dam/fedex/us-united-states/services/Service_Guide_2026.pdf
  • PSA Submission Services Terms and Conditions (last updated April 22, 2026), sections 2, 5, 6, 7 and 10, accessed Oct 21, 2026: https://www.psacard.com/termsandconditions
  • FDIC, “Five Things to Know About Safe Deposit Boxes, Home Safes and Your Valuables” (last updated Aug. 1, 2023), accessed Oct 21, 2026: https://www.fdic.gov/consumer-resource-center/five-things-know-about-safe-deposit-boxes-home-safes-and-your-valuables
  • Florida Department of Financial Services, “Homeowners’ Insurance: A Toolkit for Consumers,” accessed Oct 21, 2026: https://www.myfloridacfo.com/docs-sf/consumer-services-libraries/consumerservices-documents/understanding-coverage/consumer-guides/english—homeowners-insurance-toolkit.pdf
  • Florida Department of Financial Services, Office of the Insurance Consumer Advocate, “Homeowners Insurance Policy Endorsements” (Personal Property Replacement Cost Coverage; Personal Property Exclusion), accessed Oct 21, 2026: https://myfloridacfo.com/division/ica/fullcoverage/homeowners/policyendorsements
  • Insurance Information Institute, “Special coverage for jewelry and other valuables,” accessed Oct 21, 2026: https://www.iii.org/article/special-coverage-for-jewelry-and-other-valuables

Thinking About Flood Insurance? Three Dates Florida Homeowners Should Know This Fall

When a storm like Hurricane Isaias is spinning in the Gulf, our phones light up with the same question: “Can I still get flood insurance?” The honest answer is usually “yes, but not in time for this storm.”

Flood insurance is about timing, and this fall the calendar matters more than usual. Whether you’re near the St. Johns River, on the coast in St. Johns County, or inland in Alachua or Marion County, here are three dates to know.

Date #1: The 30-Day Wait

A new policy from the National Flood Insurance Program (NFIP) generally doesn’t take effect until 30 days after you buy it, according to FEMA’s FloodSmart site. There are a few exceptions:

  • No waiting period when you buy flood coverage in connection with making, increasing, extending or renewing a mortgage (closing on a home, for example).
  • No waiting period for coverage changes made at renewal.
  • A one-day wait if your property was newly mapped into a high-risk flood zone and you buy within about a year of the new map taking effect. Ask us for your exact deadline.

Private flood policies set their own waiting periods, which vary by company.

What it means: you can’t wait for the forecast cone. The time to buy flood insurance is when the sky is clear.

Date #2: December 11, 2026, the NFIP Authorization Deadline

The NFIP needs legal authorization from Congress to operate, and Congress has to renew that authorization from time to time. On September 2, 2026, the president signed a law extending the program to December 11, 2026. FEMA says Congress must reauthorize the NFIP by 11:59 p.m. that day.

What happens if Congress doesn’t act in time? According to FEMA:

  • Existing flood policies stay in force, and FEMA would still be able to pay valid claims with available funds.
  • But FEMA would stop selling and renewing policies until the program is reauthorized.

We can’t predict what Congress will do. Still, it’s one more reason not to leave a new NFIP policy until mid-December.

Private flood insurance is outside the NFIP, so it isn’t affected by a lapse in the NFIP’s legal authorization. That makes it a useful second option to price, especially if timing gets tight.

Date #3: January 1, 2027, Citizens’ Flood Requirement Reaches Homes of Every Value

If your home is insured with Citizens Property Insurance Corporation and your policy includes wind coverage, Florida law has been phasing in a flood insurance requirement since 2023. According to Citizens, the last step takes effect January 1, 2027. From then on it covers all remaining new and renewing personal residential policies with wind coverage, regardless of flood zone or home value, except the exempt policies listed below. It applies starting with your first new or renewal policy date on or after January 1, 2027.

A few key points from Citizens:

  • Exempt: condo unit-owner policies, tenant (renter’s) contents policies and policies that exclude wind.
  • How much: flood dwelling coverage equal to or greater than your Citizens dwelling limit (Coverage A). If the NFIP can’t go that high, Citizens accepts the NFIP maximum you’re eligible for, which is $250,000 for a home in the regular program.
  • Proof: a signed Policyholder Affirmation Regarding Flood Insurance (Form CIT FW01) plus your flood declarations page, or a pending application with proof of payment.

We’ve put together a full guide: Citizens Flood Insurance Requirement: What Changes January 1, 2027.

Putting the Dates Together

Here’s how the calendar works for someone who wants an NFIP policy in place by January 1:

  • Work backward 30 days. For coverage to start January 1, an NFIP policy generally needs to be bought by about the first days of December.
  • Stay ahead of December 11. If Congress hasn’t acted by then, new NFIP policies could be on hold.
  • Check your own renewal date. The Citizens requirement is tied to your policy renewal, so pull out your declarations page and see when yours renews.

October and November are the comfortable window.

NFIP or Private Flood?

Both can work, and the right fit depends on your home:

  • NFIP: up to $250,000 building and $100,000 contents coverage for a home. Every company that sells NFIP policies uses the same rates. Contents are paid at actual cash value, and the policy doesn’t cover temporary living expenses.
  • Private flood: limits, features and waiting periods vary by company. Some offer higher limits or extras the NFIP doesn’t. If you’re with Citizens, the private policy has to meet Florida’s standards to count.

One caution: if you already have an NFIP policy at a discounted rate and switch to private flood, you could lose that discount if you return to the NFIP later. Florida law requires your agent to give you a written notice about this to sign before the switch. We’ll walk through it with you.

A Local Note for Gainesville and Alachua County

Both the City of Gainesville and unincorporated Alachua County take part in FEMA’s Community Rating System, which lowers NFIP premiums for policyholders in those communities. FEMA’s April 2026 list puts the City of Gainesville at Class 6 (a 20% discount) and unincorporated Alachua County at Class 5 (a 25% discount). The discount on your own policy can be smaller because of how NFIP rate caps work.

Let’s Get Your Flood Coverage Lined Up

McGriff-Williams is an independent agency in Gainesville, serving North Central and Northeast Florida since 1983. We write flood insurance every day, both NFIP and private options, and we’ll compare them side by side so you can choose with confidence. Call us at (352) 371-7977 or request a flood quote. More background is in our flood insurance guide.


General information, not legal or coverage advice. Coverage depends on the policy issued, its terms and underwriting. Information current as of October 15, 2026; confirm details with your agent, insurer or Citizens. McGriff-Williams Insurance is an independent insurance agency licensed in Florida and is not affiliated with FEMA, the NFIP or Citizens Property Insurance Corporation.

After Hurricane Isaias: A Fall Home Insurance Checkup for Florida Families

Short answer: After a hurricane or tropical storm, review your homeowners policy for claim deadlines, how your hurricane deductible works, whether your dwelling limit still fits the home and the roof and water terms. Remember that flood is separate. Fall is a practical time for that checkup in North Central and Northeast Florida.

Hurricane Isaias, the first hurricane of the 2026 Atlantic season, made landfall near Destin on October 9 as a Category 2 storm, according to the National Hurricane Center. It’s a good reminder for families across North Central and Northeast Florida to take a fresh look at their home insurance.

Hurricane season runs through November 30, and fall is a good time to spend 20 minutes with your homeowners policy. Here’s what we’d look at with you.

If Isaias Left Damage, Don’t Wait to Report It

If you found missing shingles, a damaged fence or a tree limb on the roof after the storm, take photos, make reasonable temporary repairs to prevent more damage (tarping a roof, for example), keep your receipts and call us or your insurance company.

Florida law also puts a clock on claims. Under section 627.70132 of the Florida Statutes:

  • A new or reopened property claim must be reported to your insurer within 1 year after the date of loss.
  • A supplemental claim (more damage from the same event that you find later) must be reported within 18 months after the date of loss.
  • For hurricane claims, the date of loss is the date the hurricane made landfall.

Small roof damage can turn into a leak months later, so if you aren’t sure, ask now.

Know How Your Hurricane Deductible Works

Florida home policies usually have two deductibles: one for hurricane losses and one for everything else (often called “All Other Perils”). The hurricane deductible is the one that surprises people.

When it applies. Under Florida law, the hurricane deductible covers damage during a specific window. It starts when the National Hurricane Center issues a hurricane warning for any part of Florida. It ends 72 hours after the last hurricane watch or warning for any part of Florida ends (section 627.4025). That’s why a storm that comes ashore hundreds of miles away can still put wind damage at your house under your hurricane deductible.

How much it is. Hurricane deductibles are often a percentage of your dwelling coverage, not a flat dollar amount. Insurers must offer choices of $500, 2%, 5% and 10% of the dwelling limit, with some exceptions for higher-value homes (section 627.701). Your insurer has to print the actual dollar amount on your declarations page. For example only: on a home insured for $500,000, a 2% hurricane deductible is $10,000.

It’s once per calendar year. Florida’s hurricane deductible applies on an annual basis. If you have a hurricane claim this year and another hurricane causes damage later in the same calendar year, with the same insurer or another insurer in the same group, you generally pay the greater of what’s left of your hurricane deductible or your All Other Perils deductible.

Do you know your hurricane deductible in dollars, and could you cover it from savings? If not, let’s talk about the trade-offs.

Check That Your Dwelling Limit Still Fits Your Home

Your dwelling coverage (Coverage A) should reflect what it would cost to rebuild your home today, not what you paid for it or what it would sell for. If you’ve redone the kitchen, added a pool or finished a bonus room since the policy was written, your limit may be behind.

Florida law requires insurers to offer replacement cost coverage on the home itself (section 627.7011). Replacement cost pays to repair or rebuild without taking off for wear and tear. Make sure that’s what you have. Ask whether you have extended replacement cost or an inflation guard, too.

Look Closely at Your Roof and Water Coverage

Two parts of Florida home policies have changed a lot in recent years:

  • Roofs. Some policies now pay roof claims on a schedule based on the roof’s age and material, and some carry a separate roof deductible. Your declarations page and endorsements will tell you which applies.
  • Water damage. Many insurers cap water damage on older homes. We covered that in Is Your Water Damage Coverage Only $10,000?

Remember: Home Insurance Doesn’t Cover Flood

Rising water from heavy rain or storm surge is flood, and a standard homeowners policy doesn’t cover it. Flood coverage is a separate policy, or in some cases an endorsement. NFIP flood policies generally take 30 days to start, so it’s not something to buy when the next storm shows up in the forecast. Our flood insurance guide walks through the options. If you’re insured with Citizens, note that its flood requirement expands to homes of every value starting with new and renewal policies effective on or after January 1, 2027 (condo unit-owner and renters policies are exempt) (details here).

For Families With More to Protect

If your home, savings and family have grown, your coverage should keep up:

  • Jewelry, art, watches and collectibles. Standard policies limit theft coverage for many valuables. Scheduling items separately can give broader coverage.
  • Personal umbrella liability. Teen drivers, a pool, a dock or a busy social calendar all add liability exposure. An umbrella policy adds a layer above your home and auto limits.
  • Wind mitigation credits. Florida insurers must offer discounts or deductible credits for qualifying hurricane-resistant features (section 627.0629). Wind mitigation reports matter mainly for homes built in 2001 or earlier. If your newer home has impact rated windows and doors, ask us whether a report would help. The inspection may be at your own cost. McGriff-Williams Insurance doesn’t do wind mitigation inspections.

Let’s Review It Together

McGriff-Williams has helped North Central and Northeast Florida families with their insurance since 1983. As an independent agency, we compare options from multiple insurance companies for you, and we’ll explain your options in plain English. For homeowners coverage in the Gainesville area, see our Gainesville home insurance page. Call us at (352) 371-7977, stop by 3501 West University Ave. in Gainesville, or request a quote or policy review.


General information, not legal or coverage advice. Coverage depends on the policy issued, its terms and underwriting. Information current as of October 2026; confirm details with your agent or insurer. McGriff-Williams Insurance is an independent insurance agency licensed in Florida.
